Take the structure most of us run or service: an SCSp qualifying as a RAIF under the Law of 23 July 2016, commitment-based and closed-ended, managed by an authorised AIFM under the Law of 12 July 2013, with a Luxembourg central administration, a depositary appointed under Article 19 of the AIFM Law and a réviseur d'entreprises agréé. Nothing in it is exotic. Yet at any given date the state of that fund is held in five places, maintained by at least three parties, in at least four formats, and none of the five is the system of record for the others.
The question in the title is therefore not a question about which software to buy. It is a question about which record is authoritative for which fact, who may write to it, who must approve the write, and how the other four records learn about it. Everything else, including the choice of tooling, follows from the answer.
Required by the Law of 10 August 1915 and kept at the registered office. In practice maintained by the administrator or domiciliation agent, often as a spreadsheet or a registrar module. It is the only record that answers "who is a partner, for how much, since when".
Subscription agreement, well-informed investor classification under Article 2 of the RAIF Law, AML/CFT file under the Law of 12 November 2004 and CSSF Regulation 12-02. For a RAIF the AML supervisor is the AED, not the CSSF, and the RC and RR sit with the AIFM or the GP. Typically a KYC utility plus a shared drive.
Lux GAAP in the administrator's accounting system. Per-partner capital accounts are either derived from the ledger or, more often, kept in a parallel workbook that is reconciled to it at period end.
Article 17 of the AIFM Law, IPEV Guidelines, the valuation committee's papers and minutes. Proposed values and approved values are usually two columns in one workbook, with the approval evidenced in a separate document.
LP capital account statements (Invest Europe Investor Reporting Guidelines), the Article 20 annual report within six months of year end, Annex IV under Article 22 via eDesk, FATCA/CRS to the ACD, RBE filings under the Law of 13 January 2019. Every figure in it is assembled from records 01 to 04.
Ask anyone who has run a year-end on this structure and the same four points come up. Each is a hand-off between two of the records above, and at each one a fact is re-keyed, re-derived or re-dated.
The register is updated from the countersigned subscription agreement. The well-informed investor classification, the KYC review date and the beneficial-owner identification live in record 02. A transfer of interests with GP consent under the LPA updates the register; whether it updates the KYC file depends on who remembers. Two further things are routinely conflated: the contracting party (a natural person, or that person's holding company) and the contact who signs the emails. The same individual investing personally and through an S.à r.l. is two partners in the register, two classifications, two KYC reviews and two capital accounts, and one person on the phone.
Drawdown notices are computed pro rata in a workbook. When the money arrives, the administrator matches it to the investor and books it. That works until an LP settles two notices in one wire, short-pays, or pays before the notice is issued. From that moment "called, not yet paid" cannot be reconstructed per notice, and the unfunded commitment is computed as commitment minus called rather than commitment minus paid-in. The Invest Europe guidelines define it as the latter, and the difference between the two figures is precisely the unsettled amount that has gone missing.
A later-closing investor signs on one date, is admitted at the closing on another and pays on a third. Equalisation runs from each earlier drawdown to the closing date, not to the signature date, and the equalisation compensation (commonly 4% Act/365 under the LPA) is income allocated to the existing partners, not a return of their capital. If the register is updated on signature, the ledger on payment and the equalisation computed to the closing, there are three dates for one event and nothing reconciles them. Book the compensation as capital and the capital account bridge and the IRR schedule are both wrong, quietly, until the auditor asks.
The valuation committee approves fair values in minutes. The NAV is struck in the accounting system from a workbook export of those values. The LP statement is composed in a document template from a third cut. AuM for Annex IV is re-derived from a fourth. For CSSF-supervised vehicles, Circular 24/856 now sets out how a NAV computation error is detected, corrected, compensated and notified, with materiality thresholds by fund type. A RAIF has no such notification duty, but the conditions that produce the error are identical; only the consequence differs.
None of this is a gap in the rules. The organisational requirements of Delegated Regulation (EU) 231/2013 describe the record we are discussing with some precision, and they bind the AIFM whether or not it has delegated the work.
Read together, the common demand is reconstruction: as of date D, who held what, on what basis, computed how, approved by whom. A set of workbooks can satisfy that demand. It satisfies it slowly, once a year, with the people who built the workbooks still in the room.
If the problem is record design, the solution is a set of design rules rather than a product category. The six below are the ones I have found hold up under a Luxembourg audit and a CSSF or AED request. They are stated as rules for the record; what software implements them is secondary.
The contracting party is the investing profile: the natural person or the legal entity that signs the subscription agreement. A user account may hold several profiles, each with its own classification, KYC review date, RBE position and capital account. The register of partners, the KYC file and the capital account are views of the same profile, not three records with a name in common. A transfer moves the profile's interest; the classification and the review date travel with it.
Admission at a closing, drawdown notice issued, payment received against a notice, transfer, distribution, valuation approved: each is an event with a date, an author and an approver. The register balance, the capital account, the unfunded commitment and the Annex IV figures are read from the event stream, never typed. A countersigned PDF is evidence of an event; it is not the event. This is the single rule that removes breaks ① to ③, because there is no longer a second record to update.
Whether an investor may be admitted or shown an offer is a function of four facts at the moment of reading: a signed subscription, a KYC file within its review date, a ticket at or above the minimum, and a classification compatible with the vehicle. Store the result as a flag and it is wrong the day a KYC review lapses. Compute it at read time and the state flips with no one editing a field. The same discipline applies to unfunded commitment, to ownership percentages (new instruments over post-money fully diluted count, not money over valuation) and to the fund-currency amount of a drawdown, which is derived from the fund's currency and is not an editable field.
A payment is matched to one or more drawdown notices, never to "the investor". Short payment, over-payment and the LP who settles two notices in one wire each remain visible as a notice-level status. An unsettled notice does not enter the IRR schedule. The bank statement itself stays in the accounting system; what the fund record needs from it is the settlement status per allocation, which is also what the depositary needs for Article 19 cash-flow monitoring.
A drawdown batch is hashed; the approver signs the hash; the system refuses an approval by the preparer. Nothing is deleted. A correction is a new event that references the one it corrects. This is Articles 65 and 66 of the Delegated Regulation in a form the CSSF can read without a walkthrough, and it is the only arrangement I know of in which the four-eyes principle survives staff turnover at the administrator.
Notice periods run on the Luxembourg business-day calendar. The GP S.à r.l. and any SPVs in the structure keep a Lux GAAP chart on the standard PCN and file via eCDF; the SCSp itself files no accounts with the RCS but its AIFM still owes the Article 20 annual report. The register carries the fields the 1915 Law expects of it. The RBE position is a derived view of the register. The capital account statement follows the Invest Europe bridge: opening balance, contributions, distributions, realised and unrealised gains, other income, management fee, non-portfolio expenses, movement in the carried interest provision, closing balance; in three columns, period, year to date and since inception, with the unrealised carried interest deduction disclosed. These are not configuration options. A system in which they are configurable has to be audited for its configuration every year.
It does not value anything. Fair value under IPEV is proposed by the investment team and approved by a valuation function independent of it, under Article 17; the record stores the proposal, the approval, the basis and the date. It does not replace the depositary's oversight under Article 19, the réviseur's opinion under Article 20, or the responsibility of the RC and RR under the 2004 Law. It does not relieve the AIFM of Circular 18/698 due diligence on the administrator that operates it. What it removes is the part of each of those functions that currently consists of asking another party for an extract and checking it against one's own.
The four breaks above are not a theory. They are the four reconciliations that every administrator in this jurisdiction performs at period end, and the four that generate the audit adjustments. The operating model that removes them is well understood; the record design that supports it is not technically demanding. What has been missing is the decision to treat the register of partners, the KYC file, the ledger, the valuation file and the reporting pack as views of one record rather than as five deliverables from five parties.
So the question to managers and service providers reading this is the one LPEA put to you: of the four, which one breaks most often in your fund, and who owns the fix?
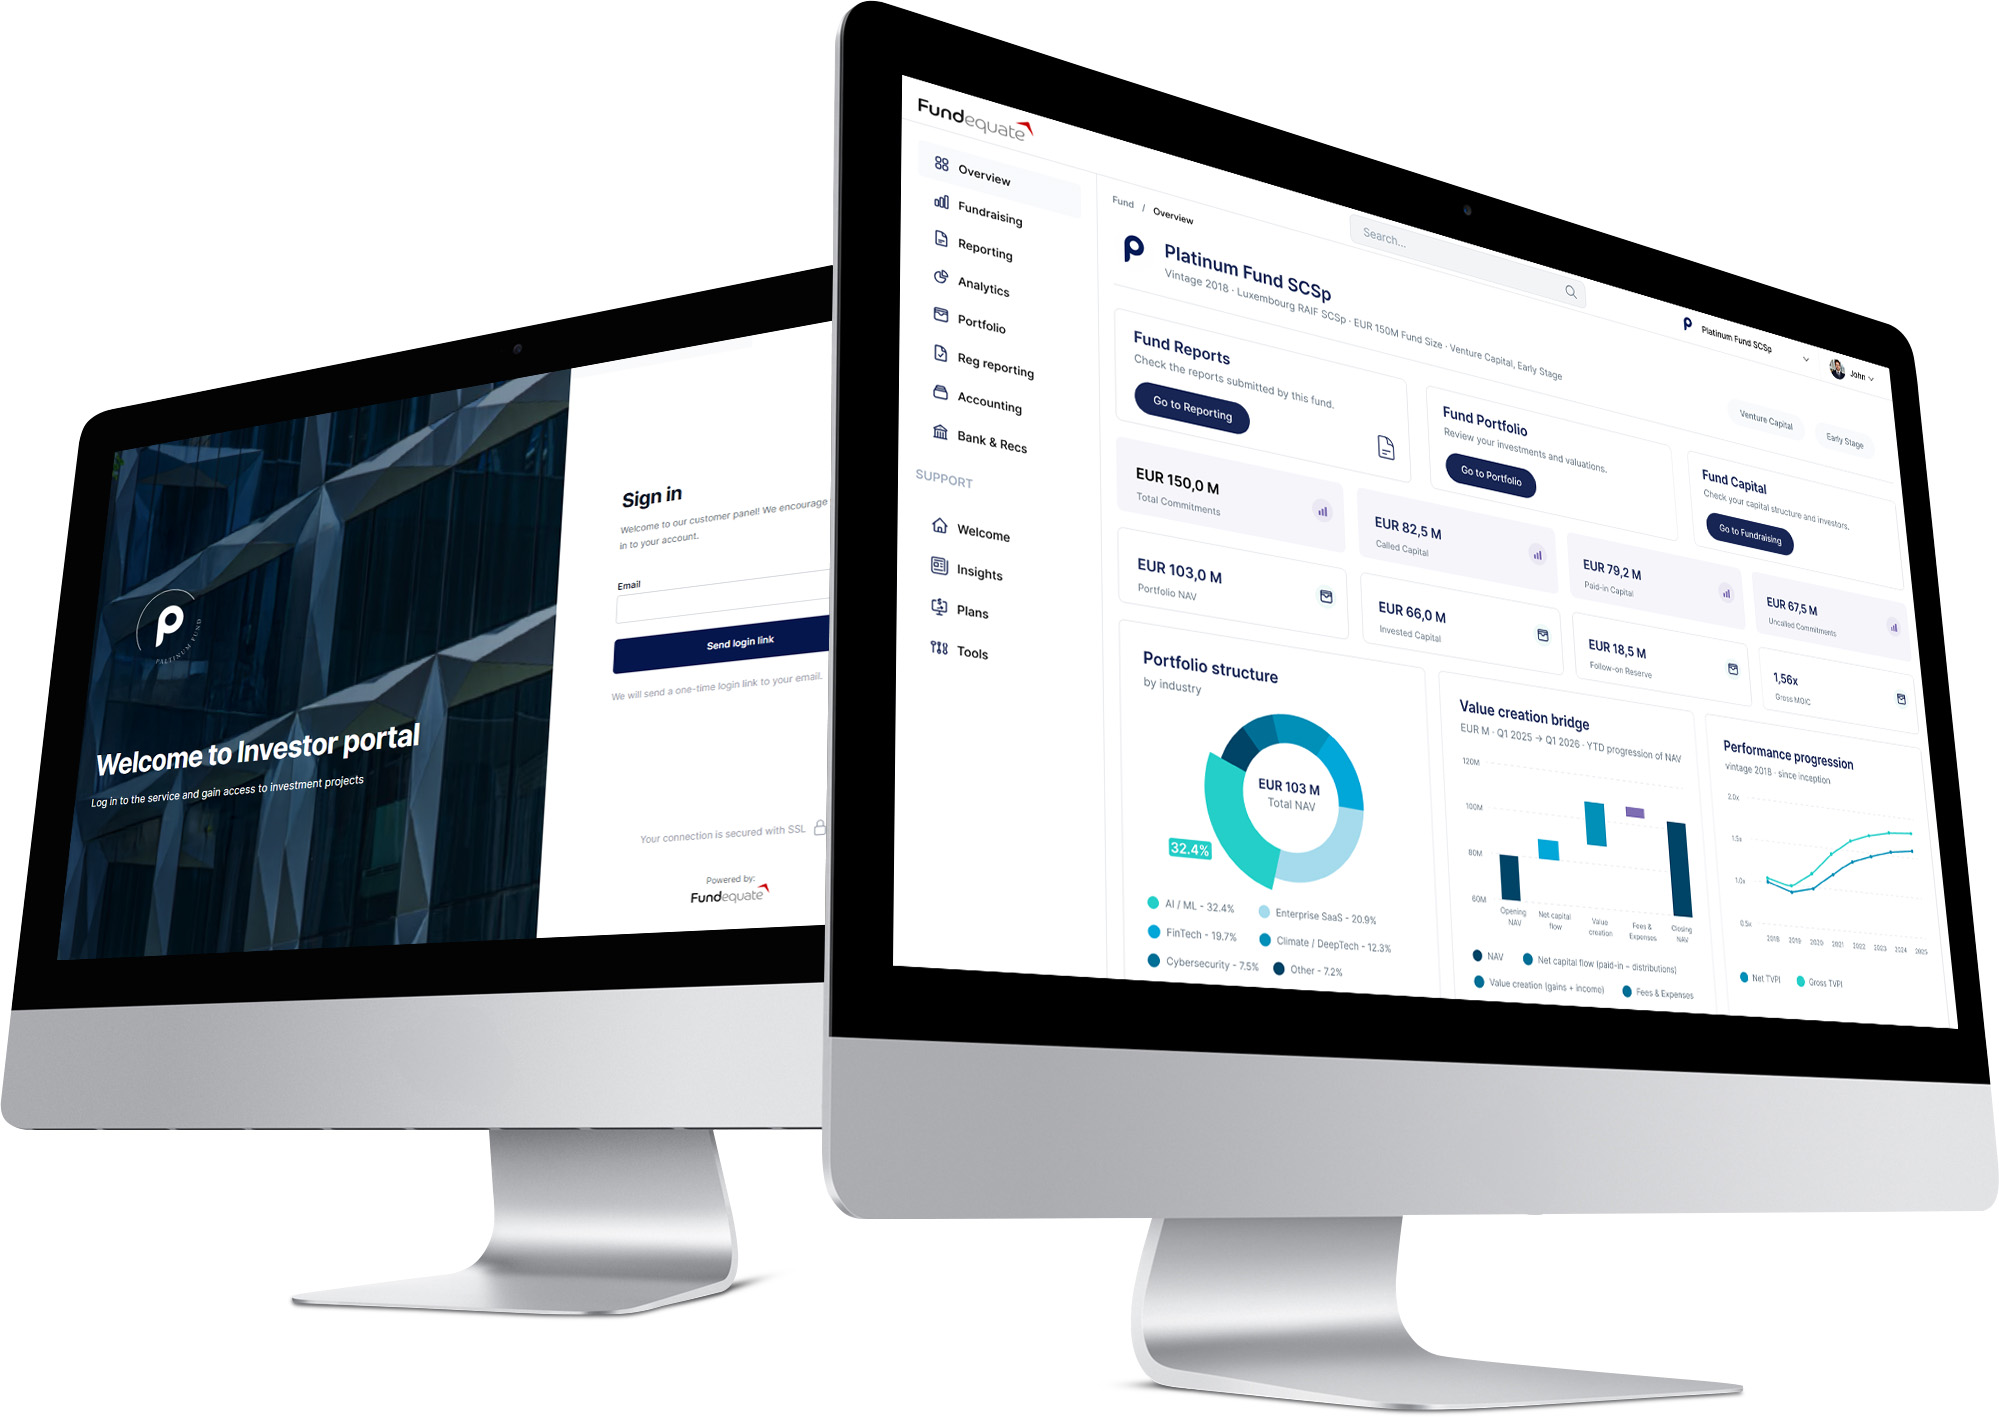
No slides and no sales deck.. Just a live closing, a capital call and a register, on data that behaves the way yours will.
Fundequate Sàrl is a company registered and domiciled in Luxembourg. We provide innovative solutions to simplify fund structuring, administration, and investor onboarding, ensuring compliance, transparency, and efficiency for fund managers and investors.


