Insights · SPVs & syndicates · Luxembourg
One legal form carries most of Luxembourg's private deal structuring: the SCSp. The same partnership that wraps a deal-by-deal SPV also carries club deals among a few families and feeder vehicles that pool investors into a master fund. The mechanics are identical; what changes is who pools the capital, who decides — and whether the vehicle is a fund in the legal sense, because the legal form never settles that question by itself.
The SCSp (société en commandite spéciale, special limited partnership) was added to the Law of 10 August 1915 in 2013, modelled on Anglo-Saxon limited partnerships for exactly this work. Four properties explain why it became the market standard:
Nearly everything in an SCSp is contract. The LPA freely sets:
What is not contractual. Beneficial owners are registered in the RBE (Law of 13 January 2019). AML/KYC under the Law of 12 November 2004 attaches to the obliged entities in the structure — the AIFM and the professional service providers — rather than to the bare legal form: an unregulated SCSp that qualifies as an AIF sits under the AED's AML supervision, with the CSSF supervising its Luxembourg AIFM, while a genuine non-AIF joint venture is not automatically subject to the fund-type AML framework (its banks and providers still run their own checks). And — the point most often missed — whether the vehicle is an AIF is decided by what it does: Article 1(39) of the Law of 12 July 2013, assessed against all elements of the definition — capital raising, pooled returns, a defined investment policy (ESMA/2013/611) — never by what the LPA calls it.
The same SCSp carries three different structures. The legal form does not change; the AIF analysis, the manager and the economics do:
| Club deal | Deal-by-deal syndicate | Feeder vehicle | |
|---|---|---|---|
| Who pools | A few known investors (families, offices) who co-decide | A lead and passive backers, one deal | A manager's investor group, into one master fund |
| Investment policy | The venture itself; investors steer it | Acquire and hold one named company | ≥85% into the master AIF (or equivalents — section 5) |
| AIF? | Not necessarily — assessed against all elements of the definition (section 4) | Usually yes | Yes — a feeder AIF |
| Manager | No AIFM required if genuinely non-AIF; corporate management remains governed by the LPA and company law | External AIFM, typically registered (Art. 3) | External AIFM; assets counted into its aggregated thresholds (with the Art. 2(4) CDR 231/2013 exclusion) |
| Economics | Pro-rata, often no carry | Carry to the lead, single-exit waterfall | Master's terms passed through; feeder-level costs disclosed |
| Distribution | The club itself — no raising | National private placement, professional investors in Luxembourg | Marketing of an AIF — regime depends on the feeder's and the master's status (section 5) |
The deal-by-deal column is the subject of the complete guide to deal-by-deal SPVs; the other two follow here.
A club deal is a handful of investors — typically families, family offices or entrepreneurs who know each other — buying one asset together. The SCSp fits because the club's bargain lives in the LPA: who contributes what, who signs for the venture, what needs unanimity, how someone exits.
The structuring question is the AIF line, and it is not binary. A genuine joint venture may fall outside the AIF definition where its participants collectively exercise direct and ongoing discretion or control over the undertaking's assets — something more than ordinary shareholder voting or reserved-matter consent rights. A veto, a seat on an investment committee or the right to approve exits does not, by itself, amount to day-to-day control. And joint-venture status is not an automatic exemption from AIFMD: the classification must be assessed against all elements of the AIF definition — capital raising, pooled returns and a defined investment policy (ESMA/2013/611, points 4–5 and 12). A second potential route out is the pre-existing group — notably a family structure investing the private wealth of an existing family group (ESMA guidelines, points 15–16) — but a handful of friendly family offices does not automatically qualify as one.
The admission of passive investors — a friend's ticket, a co-investor who only signs and pays — is a significant indicator requiring reassessment. It does not by itself determine the classification, but a club that starts raising capital from members who do not control the venture should expect the analysis to land on the AIF side.
Practical consequence: run the classification before the LPA is drafted, and document the conclusion with Luxembourg counsel. A genuine joint venture writes real, continuing joint control into the LPA and keeps it real in practice; a club that is an AIF appoints an external AIFM — below the Article 3 thresholds, a registered one — and runs its invitations accordingly. Retrofitting either conclusion after closing is expensive, and granting every LP a veto is not, by itself, a way out of AIFMD.
Two club-deal terms worth drafting with care: deadlock (joint control means the LPA needs a tie-breaker — a casting mechanism, a buy-sell, or a wind-up trigger) and transfers (a club is personal; pre-emption rights and GP consent keep it that way).
A feeder pools a defined group of investors and channels them into a master fund. Under Article 4(1)(m) AIFMD, a feeder AIF is one that invests at least 85% of its assets in a single master AIF — or in several master AIFs with identical investment strategies, or that otherwise has at least 85% of its exposure to such a master. In Luxembourg the feeder is usually an SCSp sitting between the investors and the master, so the master's register shows one limited partner instead of dozens.
Why managers build them:
What the feeder does not remove:
| SCSp | SCS | Sàrl | |
|---|---|---|---|
| Legal personality | No (own estate) | Yes | Yes |
| Constitution | Private deed | Private deed | Notarial deed |
| Minimum capital | None | None | EUR 12,000 |
| Investors in public file | No | No | Yes (shareholders) |
| Luxembourg tax | Generally transparent | Generally transparent | Opaque (CIT, NWT) |
| Typical role | Pooling vehicle: SPV, syndicate, club, feeder | As SCSp where personality is wanted | GP entity, holding layer |
Legal form and AIF status are independent axes: any of these forms can be an AIF, or not, depending on what it does. The pattern of a complete structure is an SCSp as the pooling vehicle, a Sàrl as its general partner, and — where the vehicle is an AIF — a registered or authorised AIFM as the manager. How the vehicle is then set up, run and wound down, step by step, is in the complete deal-by-deal SPV guide.
The société en commandite spéciale — a special limited partnership introduced in 2013 into the Law of 10 August 1915. Private constitution, no minimum capital, no legal personality, limited partners outside the public RCS file, generally tax-transparent. The standard wrapper for club deals, syndicates and feeders.
The regimes are nearly identical; the SCS has legal personality, the SCSp does not. The SCSp still has its own estate and is represented by its appointed managers, who may but need not be general partners.
Only where it is genuinely not an AIF. A joint venture may fall outside the definition where the participants collectively exercise direct and ongoing discretion or control over the venture's assets — more than voting or veto rights — but that is not an automatic exemption: all elements of the AIF definition are assessed (ESMA/2013/611). Admitting passive investors is a significant indicator requiring reassessment. Document the conclusion with counsel either way.
A vehicle pooling a group of investors into a master fund. Under Article 4(1)(m) AIFMD a feeder invests at least 85% of its assets in one master AIF, in several masters with identical strategies, or otherwise holds at least 85% exposure to such a master. In Luxembourg usually an SCSp — the master sees one limited partner instead of dozens.
Yes — the feeder is itself an AIF and an SCSp cannot be internally managed. Its assets are generally included in the manager's aggregated Article 3 thresholds, though an investment into another AIF managed by the same external AIFM may be excluded to avoid double counting (Article 2(4) of Regulation 231/2013).
Only where the feeder's AIFM is authorised and the master is itself an EU AIF managed by an authorised EU AIFM (Articles 31(1) and 32(1) AIFMD). A feeder into a non-EU master, or into a master run by a registered AIFM, relies on national private placement regimes instead.
Generally yes in Luxembourg — no entity-level income tax and no withholding on distributions. Watch Article 14(4) LITL (corporate GP at 5% or more) and the reverse-hybrid rules of Article 168quater LITL — triggered by associated investors at 50% or more and a classification mismatch, not by geography alone — checked per investor base before first closing.
Fundequate Platform implements six record-design rules for Luxembourg AIFs: one investor identifier, dated events, preserved calculations, notice-level reconciliation, four-eyes approval and LPA-controlled configuration.
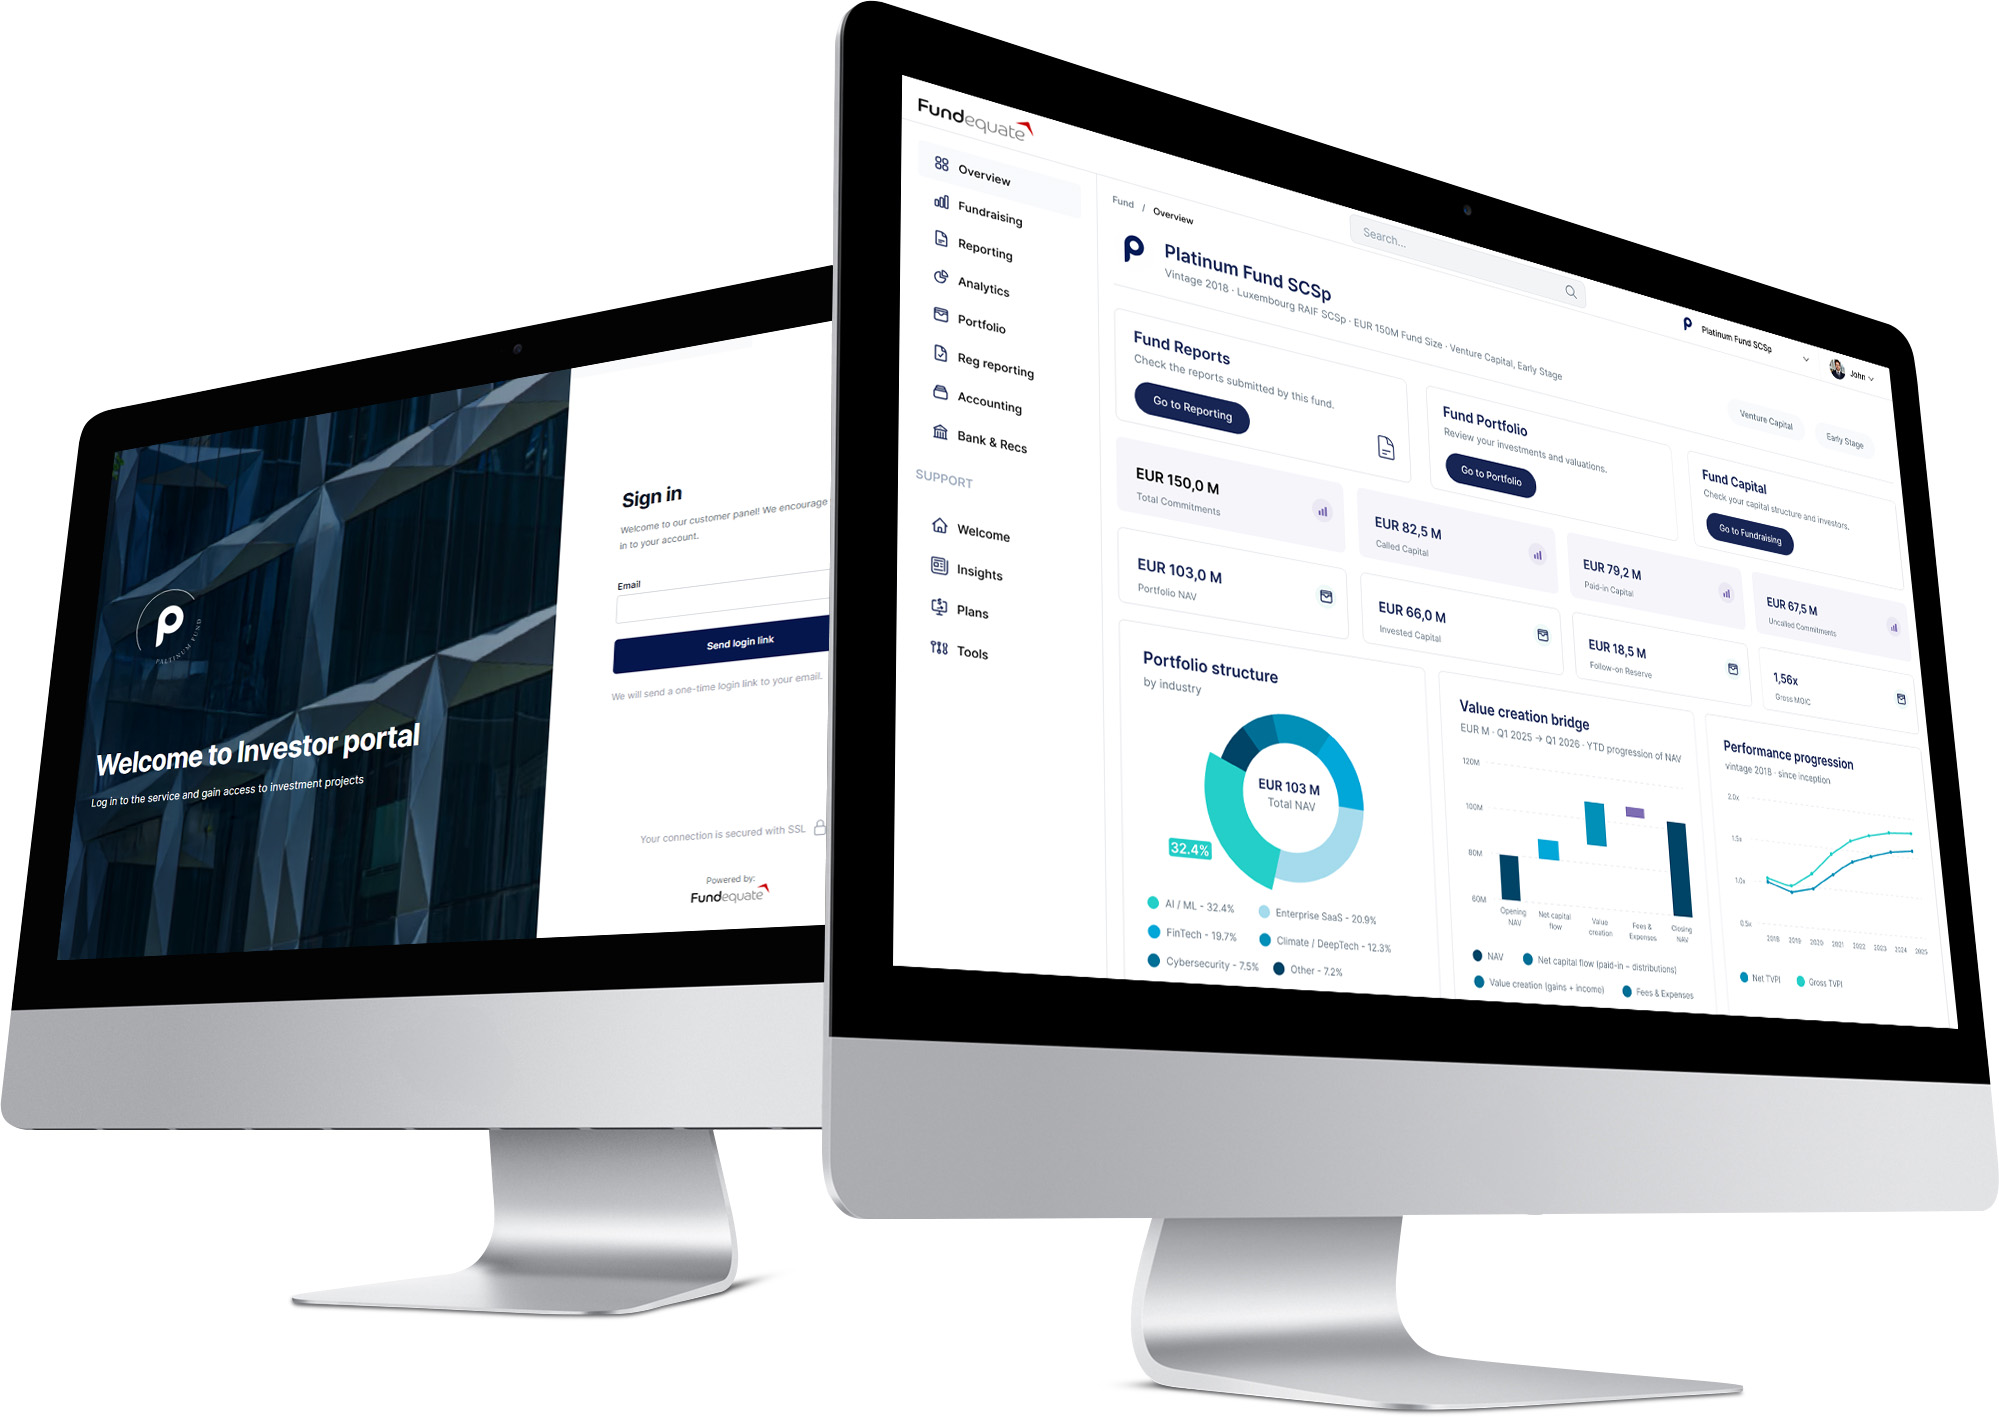
Investor onboarding, commitments and closings, capital calls, distributions, capital accounts and waterfall — with an LP portal, full audit trail and Invest Europe-aligned reporting.
Incorporation, RCS and RBE registration, bookkeeping, statutory accounts, VAT and annual filings, registered office and Luxembourg-resident management — the full substance layer for your fund vehicle.
Fundequate Sàrl is a company registered and domiciled in Luxembourg. We provide innovative solutions to simplify fund structuring, administration, and investor onboarding, ensuring compliance, transparency, and efficiency for fund managers and investors.


Fundequate Sarl
2 Rue Siggy vu Letzebuerg
L-1933 Luxembourg
contact@fundequate.com
Tel. +352 661 324 404
