Insights · SPVs & syndicates · Luxembourg
Every structuring decision in a Luxembourg investment vehicle hangs on one classification: is it an alternative investment fund? The answer decides whether a manager must be appointed, who may be approached for money and what is reported to the CSSF, yet it is routinely assumed rather than tested. This is the test, element by element, with the exemptions and the consequences of getting it wrong.
An alternative investment fund is a collective investment undertaking which raises capital from a number of investors, with a view to investing it in accordance with a defined investment policy for the benefit of those investors, and which does not require authorisation as a UCITS, Article 4(1)(a) of Directive 2011/61/EU (AIFMD), transposed in Luxembourg as Article 1(39) of the Law of 12 July 2013, as amended (most recently by the Law of 3 March 2026 transposing AIFMD II, which left the AIF definition itself untouched).
Three things follow from the drafting. The definition attaches to any undertaking, an SCSp, a Sàrl, an SA, a contractual arrangement, regardless of legal form, open- or closed-ended structure, or listing. There is no size floor: a EUR 2 million vehicle can be an AIF (size matters only for which AIFM regime applies). And the words are read through the ESMA Guidelines on key concepts of the AIFMD (ESMA/2013/611), which every EU regulator, the CSSF included, applies to the facts of the vehicle, not to its name.
An undertaking that pools capital for a pooled return, where the unitholders, as a group, have no day-to-day discretion or control over its assets. Ordinary shareholder rights, vetoes or reserved-matter consents do not amount to day-to-day control; genuine, continuing joint management of the assets by all participants can. An undertaking with a general commercial or industrial purpose, running a business rather than an investment, sits outside this element.
Capital raising means taking direct or indirect steps to procure capital from investors, one round of commitments at formation is enough; no public offer is needed. A single investor does not automatically defeat this element: it is met where the vehicle's binding documents do not prevent raising from further investors, or where the sole investor is itself a conduit pooling several underlying investors. Conversely, an undertaking investing only the private wealth of a pre-existing group, the ESMA guidelines' family-office discussion, does not "raise capital" in this sense.
A policy on how pooled capital is to be managed to generate a pooled return, fixed by the time commitments become binding and typically binding on the undertaking. It does not need to be elaborate: "acquire and hold shares in company X" is a defined investment policy. Breadth is not an escape, a policy to "invest opportunistically in European technology" still qualifies.
The undertaking seeks to generate a pooled return for its investors through the acquisition, holding or disposal of investment assets. The return does not need to be distributed pro rata: different investor classes, preferred returns and carried interest arrangements are fully compatible with a collective investment undertaking, what matters is the shared investment risk, which distinguishes it from, say, a captive treasury vehicle run for a single group's operational purposes.
The elements are cumulative and the analysis is holistic: the ESMA guidelines warn against reading any single criterion in isolation. The absence of an essential element of the statutory definition, a true general commercial purpose, genuine collective day-to-day control, no capital raising from a pre-existing family group, may place an undertaking outside its scope; but no single indicative characteristic in the guidelines is an automatic safe harbour, and a label never is.
Even a vehicle meeting the definition can sit outside AIFMD under Article 2(3):
Two frequently invoked carve-outs are not in the exemption list but in the guidelines and recitals: the joint venture (participants collectively exercise direct, ongoing discretion over the assets, more than vetoes and committee seats) and the family vehicle investing the private wealth of a pre-existing group without raising external capital. Both are fact patterns to be evidenced, not boxes to tick, the detail is in our SCSp guide for club deals and feeders.
| Vehicle | Typical outcome | What drives it |
|---|---|---|
| Deal-by-deal SPV (lead + passive backers) | AIF | Capital raised from passive investors, defined single-asset policy, see the deal-by-deal guide |
| Club deal with genuine joint control | Often non-AIF | Direct, ongoing collective discretion over the assets, evidenced in the LPA and in practice |
| Feeder into a master fund | AIF | Raises from a number of investors; the policy is investing into the master |
| Wholly-owned acquisition subsidiary | Typically non-AIF | Functions within a corporate group and raises no capital for collective investment, but single ownership alone is not determinative: purpose, capital-raising arrangements and policy are checked |
| SOPARFI with outside investors and exit-driven returns | Case by case | The holding exemption fails where the main purpose is investor returns through divestments |
| Securitisation vehicle (2004 Law) | Case by case | Excluded only where it qualifies as a securitisation special purpose entity within the AIFMD definition; otherwise the AIF test applies |
If the vehicle is an AIF: it needs a manager. An SCSp cannot be internally managed, so an external AIFM is appointed: below the thresholds of Article 3 of the 2013 Law, a registered AIFM; above them, or by opt-in, an authorised one. The thresholds: EUR 100 million including assets acquired through leverage as the general limit, or EUR 500 million where the portfolios are unleveraged and grant no redemption rights exercisable during five years from each AIF's initial investment, in each case aggregated across all AIFs the manager runs. Offering or placing the vehicle's units at the initiative of the AIFM or on its behalf is regulated marketing, assessed also under the rules of each investor's jurisdiction, though not every contact with a prospective investor meets that definition. Regulatory reporting applies, with its frequency and scope set by the AIFM's status, assets under management and the applicable reporting rules, and the AML framework of the fund sector attaches.
One targeted carve-out sits in Article 3(1) of the 2013 Law (Article 3(1) AIFMD): the Law does not apply to an AIFM managing AIFs whose only investors are the AIFM itself or entities of its own group, provided none of those investors is itself an AIF. It exempts the manager in a purely intragroup setting. It does not turn the vehicle into a non-AIF, and it falls away the moment an outside investor enters.
If the vehicle is not an AIF: the conclusion is an asset, but only when documented. A reasoned counsel memo, written before launch, is what the bank's onboarding team, the auditor and any institutional counterparty will ask for, and it is the basis on which the CSSF's questions are answered. An undocumented "we think we're out of scope" is worth little three years later at exit.
Managing an AIF without the required registration or authorisation breaches the Law of 12 July 2013, which arms the CSSF with administrative sanction and injunction powers. The practical costs usually arrive earlier and hurt more: a bank that freezes onboarding until the status is clarified, an auditor who qualifies, a master fund or institutional investor that walks, marketing done without a legal basis that cannot be retro-fitted, and a mid-life regularisation, appointing an AIFM, repapering documents, notifying the regulator, executed under time pressure. The classification memo costs a fraction of any of these.
Rule of thumb: run the AIF test before the term sheet, not after the closing. If the answer is "AIF", the manager, the invitation plan and the reporting are design inputs; if the answer is "non-AIF", write it down and keep the facts matching the memo.
A collective investment undertaking which raises capital from a number of investors, with a view to investing it in accordance with a defined investment policy for the benefit of those investors, and which is not a UCITS, Article 4(1)(a) AIFMD, Article 1(39) of the Luxembourg Law of 12 July 2013, read through the ESMA Guidelines ESMA/2013/611.
No, but the label decides nothing. A vehicle pooling passive outside investors under a defined policy typically is; a wholly-owned acquisition subsidiary, a genuine joint venture or a securitisation vehicle typically is not. The facts decide, element by element.
Article 2(3) excludes, among others, holding companies within Article 4(1)(o), IORPs, supranationals and central banks, government social-security bodies, employee participation and savings schemes, and securitisation special purpose entities within the AIFMD meaning, a 2004-Law vehicle does not qualify automatically. Joint ventures and family vehicles are guideline-based carve-outs, not listed exemptions.
Not automatically either way. The exemption covers companies running a business strategy through subsidiaries on their own account, listed on an EU regulated market or not set up mainly to generate investor returns through divestments. A SOPARFI pooling investor money for exit-driven returns can be an AIF; a group holding entity generally is not.
The parties classify it themselves before launch, against the statute and the ESMA guidelines, and the CSSF can challenge the classification. In practice the analysis lives in a counsel memo, because banks, auditors and counterparties ask for it.
It breaches the Law of 12 July 2013, with the CSSF's administrative sanctions and injunctions available. The earlier, larger costs are practical: frozen bank onboarding, qualified audits, lost investors, marketing without a legal basis, and a forced mid-life regularisation.
Yes, a joint venture that admits passive investors, a family vehicle that takes outside money or a holding that starts raising for exit-driven returns can grow into the definition. Re-test whenever the investor base or purpose changes.
Fundequate Platform implements six record-design rules for Luxembourg AIFs: one investor identifier, dated events, preserved calculations, notice-level reconciliation, four-eyes approval and LPA-controlled configuration.
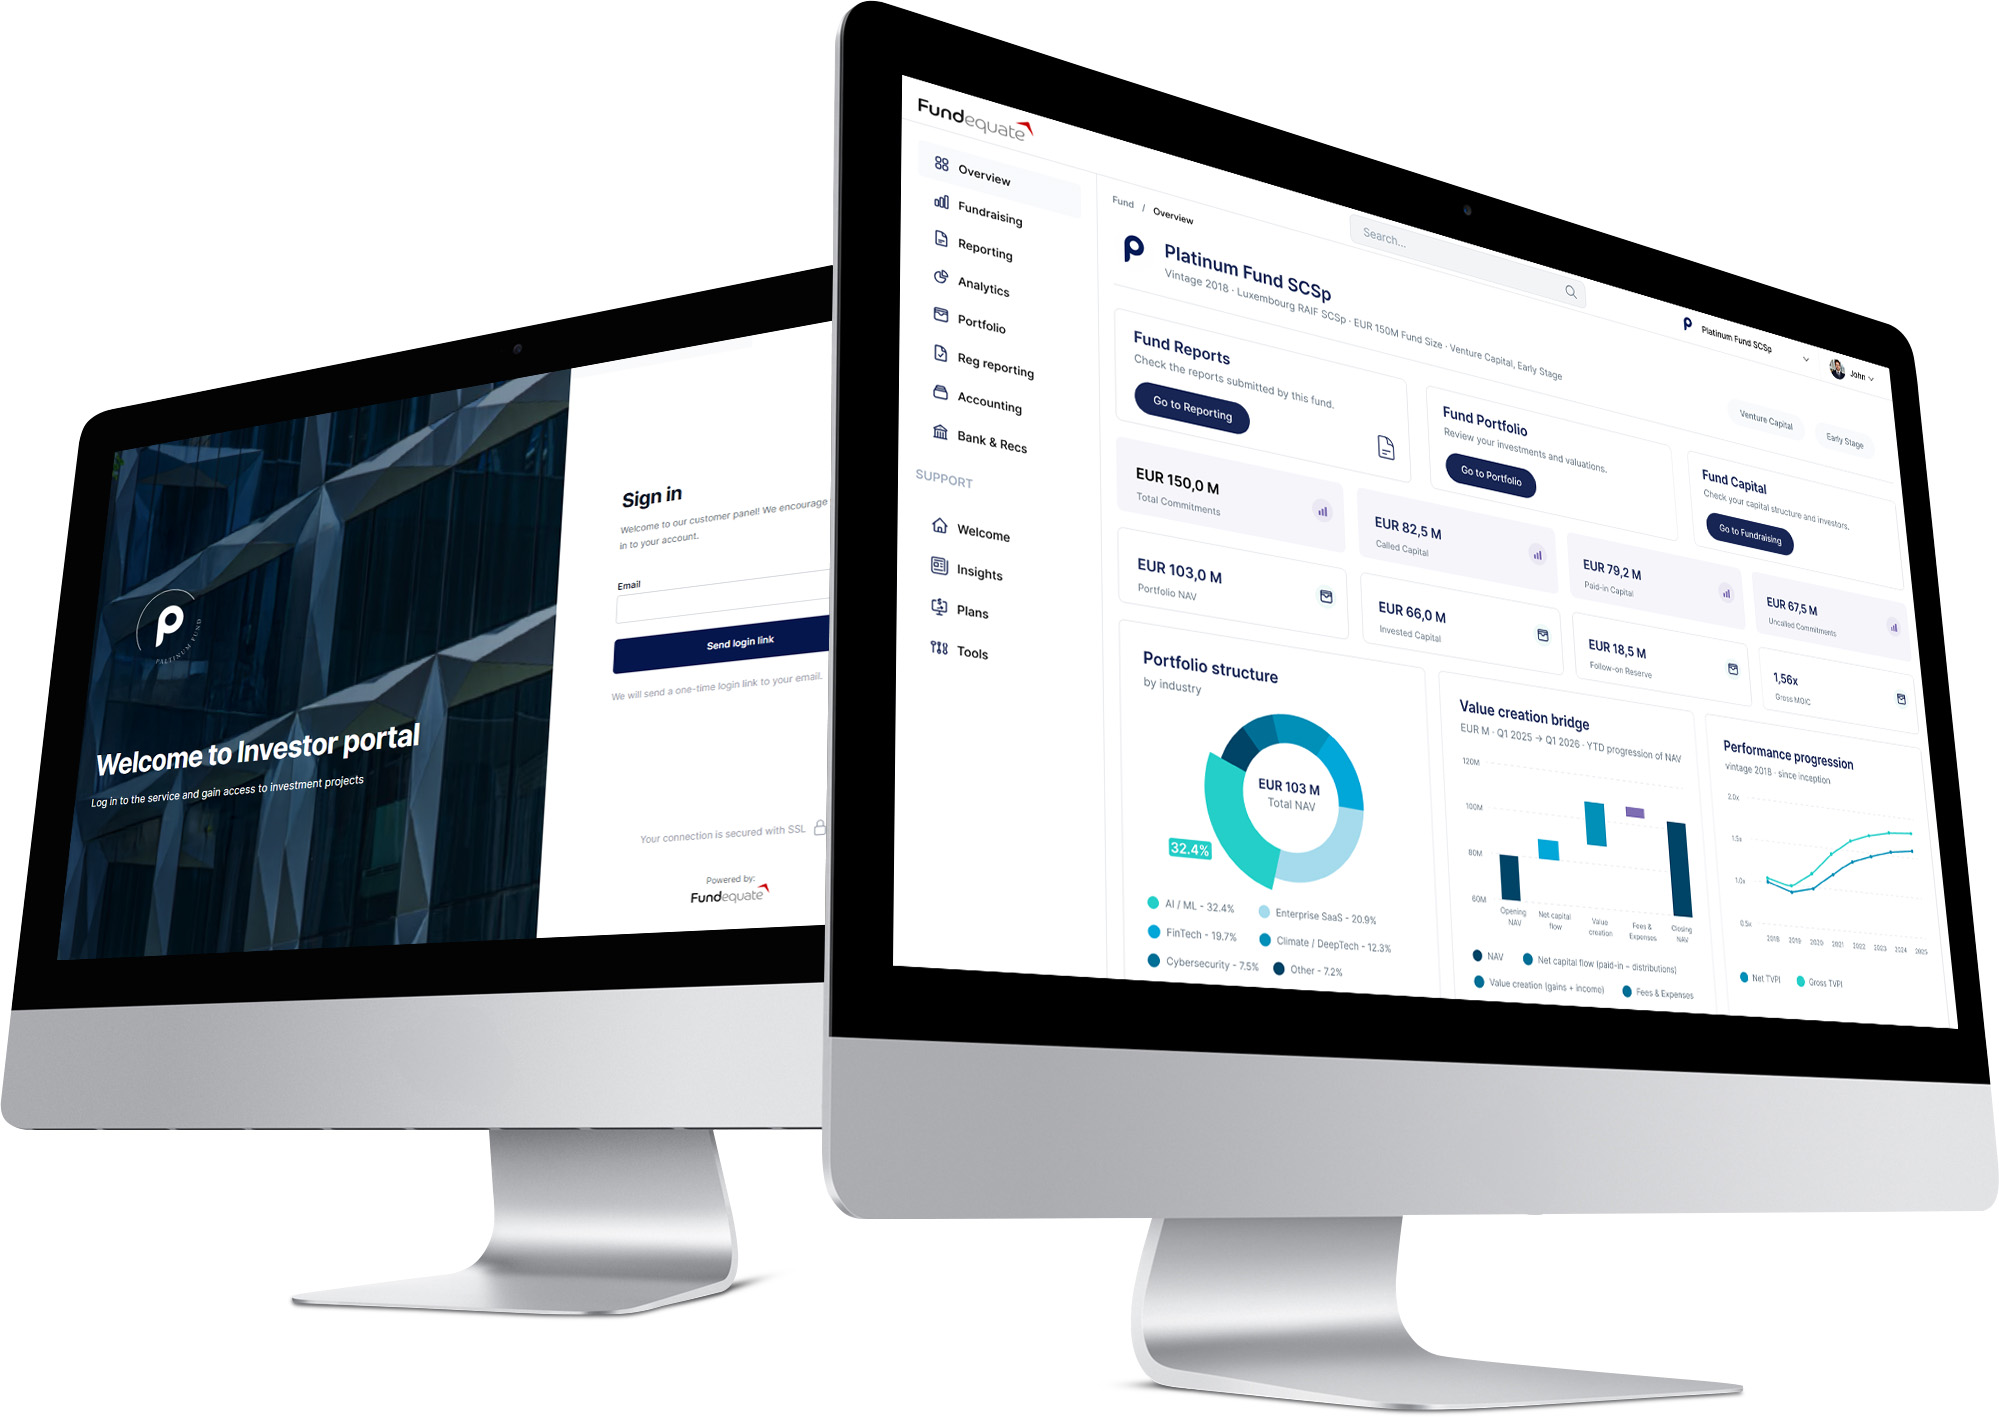
Investor onboarding, commitments and closings, capital calls, distributions, capital accounts and waterfall — with an LP portal, full audit trail and Invest Europe-aligned reporting.
Incorporation, RCS and RBE registration, bookkeeping, statutory accounts, VAT and annual filings, registered office and Luxembourg-resident management — the full substance layer for your fund vehicle.
Fundequate Sàrl is a company registered and domiciled in Luxembourg. We provide innovative solutions to simplify fund structuring, administration, and investor onboarding, ensuring compliance, transparency, and efficiency for fund managers and investors.


Fundequate Sarl
2 Rue Siggy vu Letzebuerg
L-1933 Luxembourg
contact@fundequate.com
Tel. +352 661 324 404
