A distribution waterfall is the contractual mechanism that determines how proceeds received by an investment vehicle are allocated between its investors and the persons entitled to carried interest. For a Luxembourg special limited partnership (société en commandite spéciale, or SCSp), it is defined in the limited partnership agreement (LPA): when investors recover their capital, whether they receive a preferred return, when carried interest becomes payable and how the remaining profit is divided.
Consider an SCSp that invests in a venture capital company. Investors contribute EUR 1 million; five years later the SPV receives EUR 3 million from selling its shares. The investment has produced EUR 2 million above contributed capital before any further costs, taxes or reserves, but investors do not automatically receive EUR 3 million. If the LPA provides for 20% carried interest on qualifying profit, part of the proceeds goes to the carry holder; if it also provides for a preferred return, a catch-up or distribution reserves, those provisions change the sequence and timing of payments.
These are separate calculations. An SPV holding preferred shares may receive EUR 2 million from a EUR 20 million company sale; its carry is calculated on its own contractual economics, not on the company's sale price. The calculation also depends on whether the SPV receives cash, listed shares, escrowed consideration or future earn-out payments.
The SCSp suits contractual distribution arrangements because the Law of 10 August 1915 on commercial companies leaves the partners wide freedom to define their economic rights: the LPA may provide for differentiated allocations of profits and distributions. Luxembourg law prescribes no standard 20% carry, 8% hurdle or catch-up mechanism for an ordinary SCSp. These are commercial terms, not statutory percentages, and the LPA must translate them into enforceable, calculable provisions.
In an SCSp syndicate the parties are typically:
The carry holder does not have to be the corporate GP, and in practice carry is commonly held outside it to manage municipal business tax risk under Article 14(4) of the Luxembourg Income Tax Law. The legal form is covered in our guide to the Luxembourg SCSp.
A conventional private equity waterfall has four successive tiers. Not every Luxembourg SPV uses all four; single-asset syndicates often use a simpler two-tier arrangement.
| Tier | Distribution priority | Economic purpose |
|---|---|---|
| 1 | Return of capital | Investors recover the capital defined in the LPA |
| 2 | Preferred return | Investors receive their contractual hurdle, if any |
| 3 | Catch-up | The carry holder receives an agreed share of distributions until the target profit-sharing ratio is reached |
| 4 | Residual split | Remaining proceeds are shared, commonly 80% to investors and 20% to carry |
The first tier returns the investors' contributed capital, and the LPA must define what counts as capital: the amount used to acquire the investment; that amount plus establishment expenses; all capital contributed, including fees, operating costs and reserves; or, in a multi-asset vehicle, the capital attributable to the realised investment. The choice drives the carry.
An SPV that raises EUR 1 million and spends EUR 40,000 on set-up and operating costs has EUR 960,000 available to invest. If the LPA requires all EUR 1 million to be returned before carry, the first EUR 1 million of distributable proceeds belongs to investors. Calculating carry against the EUR 960,000 acquisition cost alone, ignoring expenses funded by investors, is wrong unless the agreement expressly provides that basis.
A preferred return gives investors priority over the carry holder up to a contractual return threshold. The commonly illustrated rate is 8% a year, but it is negotiable. The LPA specifies the rate; simple or compound accrual; the start date; whether it applies to all contributed capital or only invested capital; how distributions reduce the outstanding balance; and how later calls and partially returned capital are treated.
On EUR 1 million outstanding for exactly two years, an 8% simple preferred return is EUR 1,000,000 × 8% × 2 = EUR 160,000; compounded annually it is EUR 1,000,000 × (1.08² − 1) = EUR 166,400. The same headline rate produces a EUR 6,400 difference. Real calculations use the LPA's day-count and compounding conventions and the actual dates of each contribution and distribution. A preferred return is a priority in the allocation of available proceeds, not a guaranteed return.
Under a 100% catch-up, all distributions in this tier go to the carry holder until it has received the agreed carry percentage of cumulative profit. With 20% carry, the catch-up needed is the preferred return × 20% ÷ 80%: on a EUR 160,000 preferred return, EUR 40,000. The formula assumes a full catch-up and no earlier distributions that change the calculation. The catch-up does not add carry on top of the agreed percentage; it brings the carry holder up to the contractual sharing ratio.
Once the earlier tiers are satisfied, the remaining profit is divided as the LPA provides, conventionally 80% to the limited partners and 20% to the carry holder; 85/15 and 90/10 are also common, and ratios can vary by investor class or performance threshold. Where the LPA requires a cumulative waterfall, the sequence is recalculated cumulatively at each distribution rather than restarted.
The structure most often used in single-asset syndicates. Assumptions: EUR 1,000,000 contributed; EUR 1,800,000 of exit proceeds available for distribution; no preferred return; 20% carry on profit after full return of contributed capital; no other expenses, taxes, reserves or earlier distributions; no co-investment by the carry holder.
| Calculation | Amount |
|---|---|
| Exit proceeds | EUR 1,800,000 |
| Return of contributed capital to LPs | EUR 1,000,000 |
| Profit available for sharing | EUR 800,000 |
| Carried interest: 20% × EUR 800,000 | EUR 160,000 |
| Remaining profit to LPs | EUR 640,000 |
| Total LP distributions | EUR 1,640,000 |
| Total carry-holder distributions | EUR 160,000 |
The gross multiple before carry is 1.80x; the net LP multiple after carry is 1.64x. With one terminal exit this is operationally simple. Complexity arrives with multiple closings, additional contributions, partial exits, different investor entitlements or special distributions.
Same SPV, now with an 8% simple preferred return, a 100% catch-up and a final 80/20 split. Holding period exactly two years, no interim cash flows, no other costs.
| Tier | To LPs | To carry holder |
|---|---|---|
| 1. Return of capital | EUR 1,000,000 | – |
| 2. Preferred return | EUR 160,000 | – |
| 3. 100% catch-up | – | EUR 40,000 |
| 4. Residual 80/20 split of EUR 600,000 | EUR 480,000 | EUR 120,000 |
| Total | EUR 1,640,000 | EUR 160,000 |
The final result is identical to Example 1. The preferred return and catch-up change the sequence of payments and whether the carry holder is paid when proceeds are insufficient to complete the waterfall, and they affect when carry crystallises if the SPV makes interim distributions. With a full catch-up and enough proceeds, the carry holder ends with the same 20% of profit as under a simple 80/20 split; the two structures are not equivalent at every point of the investment's life.
Return of capital takes EUR 1,000,000 and the preferred return EUR 160,000, leaving EUR 40,000, all of which goes to the carry holder under the 100% catch-up. LPs receive EUR 1,160,000 and the carry holder EUR 40,000, which is 20% of the EUR 200,000 total profit, because the remaining cash is just enough to complete the catch-up. Without a catch-up the result changes, as the next example shows.
Under a hard hurdle, the carry holder participates only in profit above the preferred-return threshold. Under a soft hurdle with full catch-up, once the hurdle is met and the catch-up completed, the carry holder participates in the whole profit. Using the EUR 1.2 million exit (capital EUR 1,000,000, profit EUR 200,000, preferred return EUR 160,000, carry 20%):
| Waterfall structure | LP distributions | Carry |
|---|---|---|
| 20% carry, no preferred return | EUR 1,160,000 | EUR 40,000 |
| 8% preferred return, full catch-up (soft hurdle) | EUR 1,160,000 | EUR 40,000 |
| 8% hard hurdle, no catch-up: 20% × EUR 40,000 | EUR 1,192,000 | EUR 8,000 |
The difference between the two hurdle designs is EUR 32,000 in this example. An LPA that says only "8% hurdle and 20% carry" leaves the most valuable question open: which profit is subject to carry, and whether the hurdle is a priority allocation, an absolute threshold or part of a catch-up mechanism.
Syndicate costs include formation and documentation, GP and AIFM fees, investor onboarding, bank charges, accounting, tax filings and liquidation. Some are charged outside commitments, others funded from them; the waterfall follows the agreed treatment. Assumptions: EUR 1,000,000 contributed; EUR 40,000 of SPV expenses paid from contributions; EUR 960,000 invested; exit proceeds EUR 1,920,000 (2.0x on invested capital); 20% carry after full return of contributions; no preferred return, no further costs or taxes.
| Item | Amount |
|---|---|
| Investor contributions | EUR 1,000,000 |
| SPV expenses | EUR 40,000 |
| Capital invested | EUR 960,000 |
| Proceeds from the investment | EUR 1,920,000 |
| Profit after returning full contributions | EUR 920,000 |
| Carry at 20% | EUR 184,000 |
| Net amount distributed to investors | EUR 1,736,000 |
The deal returned 2.0x; investors receive 1.736x after costs and carry. The investment ratio, the share of contributions actually invested in the company, is 96%, an important disclosure in small syndicates where fixed costs are a material share of commitments.
The same cost must not be deducted twice. If the EUR 40,000 has already reduced the amount invested and the waterfall returns the full EUR 1 million contributed, deducting it again from distributable profit understates the carry base. Conversely, using EUR 960,000 as the capital base without protecting the EUR 40,000 of contributed expenses favours the carry holder over investors. The LPA, the fee schedule and the accounting records must use the same definitions.
| Investor | Contribution | Share | Distribution after carry |
|---|---|---|---|
| Investor A | EUR 500,000 | 50% | EUR 868,000 |
| Investor B | EUR 300,000 | 30% | EUR 520,800 |
| Investor C | EUR 200,000 | 20% | EUR 347,200 |
| Total | EUR 1,000,000 | 100% | EUR 1,736,000 |
A pro rata split works because all three invested on the same terms. With different closings or contribution dates, side letters, carry-free tickets or partial participation, the calculation runs at investor or class level.
A single-asset SPV does not always exit in one transaction: the company may be sold in stages, the SPV may sell part of its stake in a secondary, or receive liquidity through a recapitalisation. Assume EUR 1,000,000 invested, no fees, taxes or preferred return, 20% carry, and an LPA that pays carry on each realised tranche after recovering the cost allocated to it. The holding is split into Tranche A (cost EUR 600,000) and Tranche B (cost EUR 400,000).
First exit. Tranche A is sold for EUR 1,400,000: profit EUR 800,000, carry EUR 160,000, LPs EUR 1,240,000.
Second exit at a loss. Tranche B is sold for EUR 100,000, a loss of EUR 300,000.
| Item | Amount |
|---|---|
| Total proceeds | EUR 1,500,000 |
| Total original investment | EUR 1,000,000 |
| Lifetime profit | EUR 500,000 |
| Correct lifetime carry at 20% | EUR 100,000 |
| Carry allocated at the first exit | EUR 160,000 |
| Excess carry | EUR 60,000 |
If the LPA retains 50% of each carry entitlement in escrow, EUR 80,000 is paid at the first exit and EUR 80,000 retained. At final liquidation, lifetime carry is EUR 100,000: EUR 60,000 of the escrow goes to the LPs and EUR 20,000 is released to the carry holder. The final position reconciles to the cash:
| Final distribution after two exits | Amount |
|---|---|
| LPs: first exit | EUR 1,240,000 |
| LPs: second exit | EUR 100,000 |
| LPs: escrow correction | EUR 60,000 |
| Final LP distributions | EUR 1,400,000 |
| Final carried interest (EUR 80,000 paid + EUR 20,000 released) | EUR 100,000 |
| Total proceeds reconciled | EUR 1,500,000 |
Real agreements also deal with taxes on carry already paid, ownership of and interest on the escrow, and the enforceability of repayment.
Carry calculated on an early profitable realisation may not equal carry earned over the whole investment. A cumulative waterfall that defers carry until all contributed capital is returned reduces that risk without always removing the need for reconciliation.
An escrow retains cash before it reaches the carry holder; a clawback is a contractual obligation to return over-distributed carry when the final entitlement is lower than what was paid. They are often used together. A clawback clause states who is liable, whether the obligation is gross or net of personal taxes, when it is tested, what security backs it and how repayment is enforced. Institutional guidance such as the ILPA Principles 3.0 stresses transparent carry calculations and safeguards against excess distributions.
The terms describe economic models, not the domicile of the fund; a Luxembourg SCSp can adopt either.
| Feature | European (whole-of-fund) | American (deal-by-deal) |
|---|---|---|
| Capital-return basis | Aggregate contributed capital of the vehicle | Capital associated with realised investments, subject to adjustments |
| Timing of carry | Usually later | Potentially earlier |
| Unrealised positions | More protection before carry is paid | Exposure to later losses |
| Clawback risk | Generally lower | Generally higher |
| Carry escrow | May still be appropriate | Particularly important |
| Typical context | Multi-investment PE or VC fund | Deal-by-deal fund or hybrid structure |
The ILPA Model LPA provides separate economic models for whole-of-fund and deal-by-deal waterfalls. For an SCSp holding a single investment with one final cash distribution, whole-of-fund and deal-by-deal waterfalls may produce the same result where the capital-return basis, expense treatment, preferred return and catch-up provisions are equivalent; differences in those definitions produce different allocations even with a single investment. The models diverge further with partial exits, follow-on funding, dividend recapitalisations, several investments or unequal participation, so the model should follow the actual cash-flow profile of the deal, not the label. The structure of single-deal vehicles is explained in our deal-by-deal SPV guide.
The waterfall should be drafted so that the administrator can calculate it from the transaction records without undocumented commercial assumptions.
| LPA provision | Calculation or operational question |
|---|---|
| Distributable proceeds | What cash is available after taxes, liabilities, transaction costs and reserves? |
| Return-of-capital base | Are investment cost, establishment expenses and fees included? |
| Hurdle | What rate, accrual method, start date and compounding convention? |
| Catch-up | Who receives it, at what rate and up to what threshold? |
| Carry percentage | Constant, or tiered by performance? |
| Carry recipient | Held directly, contractually or through a carry vehicle? |
| Partial realisations | Carry by realised tranche or on cumulative performance? |
| Follow-on investments | How are additional contributions and their holding periods recorded? |
| Distribution reserves | What may be retained for liabilities, tax or future costs? |
| In-kind distributions | When is carry calculated, how are assets valued and how is it settled? |
| Escrow and clawback | How are excess distributions secured, recalculated and recovered? |
| Investor-specific terms | How are late closings, equalisation, exclusions and side letters reflected? |
A preferred return accruing from the date investors fund gives a different result from one accruing from the acquisition date. The LPA states the day-count basis, for example actual days over 365, and how partial returns of capital reduce future accrual.
An SPV may receive EUR 2 million from an exit without EUR 2 million being distributable. Agreed transaction expenses, liabilities, foreign withholding taxes, unpaid vehicle expenses and approved reserves come first; escrowed proceeds and earn-outs enter the waterfall only when released or received. The LPA defines both the distributable amount and the point at which proceeds enter the waterfall.
An IPO or a share-for-share acquisition may leave the SPV holding securities rather than cash. The LPA addresses valuation, transfer restrictions, whether an in-kind distribution triggers carry, how the carry holder receives its share and whether enough liquidity remains for expenses and taxes. The reporting fair value of an asset is not cash available for distribution.
The waterfall decides who is economically entitled to proceeds; tax law decides how that entitlement is characterised and taxed in each recipient's hands. Three points connect the two:
The waterfall is an operating calculation linked to the books, not a spreadsheet built when the exit arrives. The records it draws on are commitments, contributions, cost basis, operating expenses, realised proceeds, valuation movements, previous distributions and the carry allocation history.
An unrealised increase in a start-up's valuation does not by itself allow carry to be distributed: valuation and accounting policies govern recognition and presentation, the LPA governs entitlement. The IPEV Valuation Guidelines, updated in December 2025, are the reference framework for fair value in private capital.
Enough to reconcile the payment to the LPA: distribution date, available proceeds, returned capital, allocated profit, carried interest, withholding taxes, recallable amounts where applicable and cumulative distributions. The Invest Europe Investor Reporting Guidelines (2024) also address disclosure of realised and unrealised carry, escrow balances and potential clawback exposure.
Before any distribution is approved, the GP and the administrator reconcile the calculation to the records. The core control is: distributable cash = LP distributions + carry payments + escrow allocations, with any amounts retained for liabilities or reserves shown separately. An escrow allocation is not a cash distribution: where the escrow stays on the SPV's balance sheet as restricted cash, it is presented and reconciled according to its legal and accounting structure until it is released. The waterfall reconciles to the partner capital accounts and the cash movements. A calculation can be arithmetically correct and still wrong if it uses outdated commitments, the wrong investment cost, the wrong compounding basis or an unrecorded earlier distribution.
For sponsors and syndicate leads the difficulty is rarely knowing that carry is 20%. It is applying the right percentage to the right base, at the right time, from records that stay consistent through the life of the investment.
Fundequate combines Luxembourg expert-comptable expertise, specialised SPV operations and a proprietary digital platform. Commitments, capital calls, contributions, capital accounts, distributions and reporting sit on one set of records, and authorised users access their financial data and reports online through the investor portal. The LPA's economic terms are translated into an auditable calculation supported by the vehicle's books, connecting:
The GP and the AIFM keep their legal and regulatory decision-making responsibilities; accounting and operations provide the calculations and records behind them. This matters most for repeat syndicates and deal-by-deal programmes, where one sponsor runs several SCSps with different investors, carry rates, hurdles or follow-on terms, each of which needs its own correct calculation and books.
A defensible waterfall is one that investors can understand, the administrator can reproduce and the GP can reconcile to the LPA and the books. See our syndicate and SCSp solutions, accounting and reporting and fund documentation services.
According to the waterfall in the limited partnership agreement. In a simple structure with no hurdle and 20% carry, the carry holder receives 20% of the profit after investors recover their contributed capital. More complex agreements add a preferred return, a catch-up, expense treatment and cumulative calculation.
No. Luxembourg law imposes no standard carry rate on an ordinary SCSp. The percentage is a commercial term agreed by the parties and documented in the LPA; 15% and 10% are also common.
A priority entitlement for investors, calculated at the contractual annual rate, before carry is allocated. Its value depends on contribution dates, holding period, compounding convention and earlier distributions. It is not a guaranteed 8% return.
A waterfall tier in which the carry holder receives all distributions until its cumulative share reaches the agreed profit-sharing ratio. It follows the preferred-return tier in a conventional four-tier waterfall.
Under a hard hurdle, carry applies only to profit above the preferred-return threshold. Under a soft hurdle with full catch-up, once the hurdle is met the carry holder catches up to its share of the whole profit. On a modest exit the difference can be several times the carry amount.
Yes, if the LPA permits it. Partial exits can produce carry distributions, but later losses or costs may create clawback exposure. A cumulative waterfall or a carry escrow reduces the risk of overpayment.
It depends on the LPA. Many agreements require all investor contributions, including amounts used for set-up and running costs, to be returned before carry is payable. Costs must be treated consistently and never deducted twice.
No. The Law of 3 February 2026 changed the personal tax treatment of qualifying carried interest. It does not amend the waterfall in an existing LPA or impose a carry rate or catch-up structure.
Fundequate Platform implements six record-design rules for Luxembourg AIFs: one investor identifier, dated events, preserved calculations, notice-level reconciliation, four-eyes approval and LPA-controlled configuration.
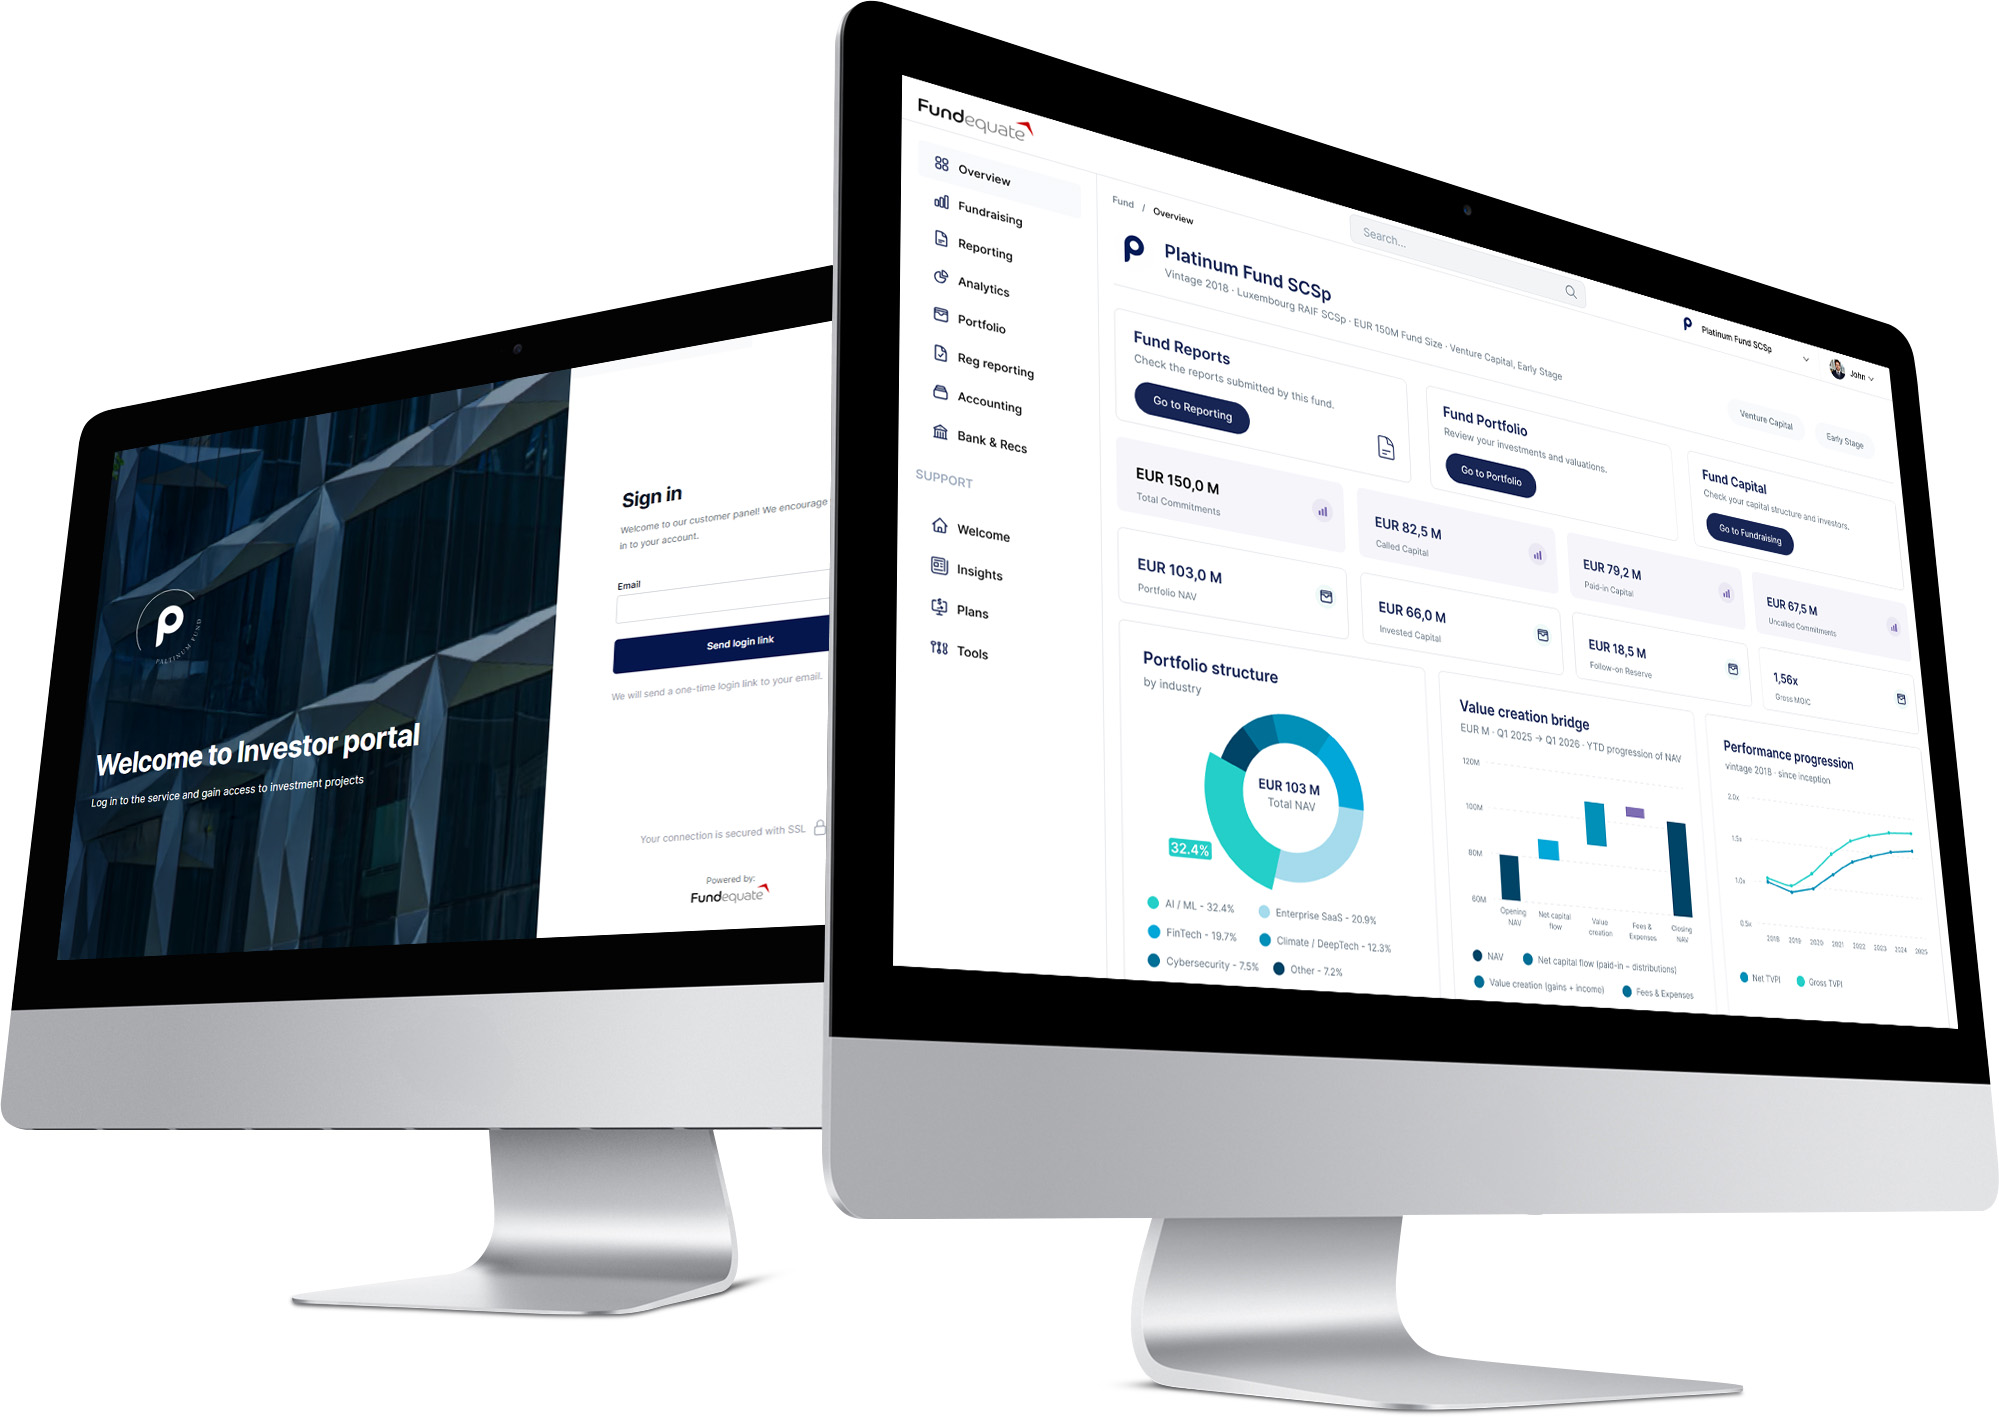
Investor onboarding, commitments and closings, capital calls, distributions, capital accounts and waterfall — with an LP portal, full audit trail and Invest Europe-aligned reporting.
Incorporation, RCS and RBE registration, bookkeeping, statutory accounts, VAT and annual filings, registered office and Luxembourg-resident management — the full substance layer for your fund vehicle.
Fundequate Sàrl is a company registered and domiciled in Luxembourg. We provide innovative solutions to simplify fund structuring, administration, and investor onboarding, ensuring compliance, transparency, and efficiency for fund managers and investors.


Fundequate Sarl
2 Rue Siggy vu Letzebuerg
L-1933 Luxembourg
contact@fundequate.com
Tel. +352 661 324 404
