
Article 3 of the Law of 12 July 2013 lets a manager whose aggregated assets under management stay below defined thresholds register with the CSSF instead of seeking full authorisation. The registered AIFM performs the same core functions as any manager of an alternative investment fund, portfolio management and risk management, but under a drastically reduced rulebook: no own-funds requirement, no depositary obligation for the unregulated AIFs it manages, no remuneration or delegation framework, and a light reporting duty.
The status presupposes that the vehicles are AIFs in the first place. Whether a given SPV crosses that line is its own analysis, covered in Is a Luxembourg SPV an AIF?; the structures a registered AIFM typically runs, deal-by-deal SPVs, syndicates, club vehicles and feeders, are described in the deal-by-deal SPV guide and the SCSp guide. In a typical set-up the general partner entity of the SCSp, or a dedicated management company in its group, takes the registered AIFM role; being the GP alone confers no manager status. The status is not limited to unregulated wrappers: subject to the thresholds and to each product's own requirements, a registered AIFM may also manage certain CSSF-authorised funds, including SIFs, SICARs and Part II UCIs. A RAIF is the exception; it must appoint an authorised external AIFM.
The registration regime is available while total assets under management stay below:
The calculation follows Articles 2 and 10 of Commission Delegated Regulation (EU) No 231/2013 and has four properties that decide real cases:
Practical rule for platforms and GP groups: keep a live register of the aggregated AUM of every vehicle under the manager and test each new SPV against the remaining headroom before it is approved. An authorisation file cannot be assembled in the 30 days the law gives after a non-temporary breach.
Registration is not a prudential authorisation, but neither is it a letter-box filing: the CSSF reviews the file, may request additional information, and issues a confirmation of registration once its assessment is complete. The content and the calendar:
There is no AIFMD own-funds requirement to evidence and no programme of operations of the kind an authorisation requires; the capital rules of the manager's legal form, and of any other licence it holds, continue to apply. The counterpart of that lightness is a set of hard limits on distribution and products, which is where the regime's real edges sit.
| Obligation | Content | Basis |
|---|---|---|
| Regulatory reporting | Annual AIFMD reporting on the main instruments traded and the principal exposures and concentrations of each AIF, filed under the applicable Annex IV reporting framework with a scope narrower than that of authorised AIFMs | Art. 3(3)(d) AIFMD; Reg. 231/2013; Circular CSSF 23/844 |
| SFDR | Applicable entity-level and product-level sustainability disclosures; SFDR covers registered AIFMs as well | Regulation (EU) 2019/2088 |
| AUM monitoring | Ongoing monitoring of aggregated AUM; at least annual recalculation; notification of breaches | Art. 3, Law of 12 July 2013; Art. 10, Reg. 231/2013 |
| Fund notifications | Notifications and information submissions concerning investment funds not authorised by the CSSF | CSSF Circular 25/894 |
| AML/CFT | Full obliged-entity framework, including the RR and RC functions and the annual compliance report. The registered AIFM itself is supervised by the CSSF for AML/CFT; a Luxembourg AIF not prudentially supervised by the CSSF, such as an unregulated SCSp, generally falls under the AED. Responsibilities are assessed separately at manager and fund level | Law of 12 November 2004 |
| Registers | RBE filings for the manager and its vehicles; registers of partners kept current | Law of 13 January 2019; Law of 10 August 1915 |
| Registration upkeep | New AIFs within 10 working days; annual update of the registration form | CSSF practice under Art. 3 |
What the registered status does not impose: AIFMD own funds, a depositary for the unregulated AIFs, the remuneration rules, the delegation framework and the liquidity management provisions that AIFMD II brought for authorised managers; the reporting burden is the narrower annual scope described above, not the full cycle of an authorised AIFM. DORA likewise does not, in principle, reach sub-threshold managers within the Article 3(2) exemption, though it can apply after a voluntary opt-in to full status. The vehicles themselves keep their ordinary company-law duties, accounting records and tax filings, as described in the deal-by-deal SPV guide.
One structured alternative exists for venture strategies: the EuVECA regime under Regulation (EU) No 345/2013. A manager below the AIFMD thresholds whose funds meet the EuVECA portfolio and investor conditions can register for the label and market it cross-border under the EuVECA passport, without full AIFMD authorisation. The conditions are specific, above all the requirement to commit at least 70% of the relevant capital base to qualifying investments, so the label fits classic venture funds better than single-asset SPVs.
When aggregated AUM exceeds the applicable threshold, the manager notifies the CSSF without delay, including where it considers the excess temporary, explaining the basis for that view; after three months the position is recalculated and the manager demonstrates that the excess has ended (Article 4 of Regulation 231/2013). Where the excess is more than temporary, and the CSSF treats an excess likely to last over three months as non-temporary, the application for full authorisation is due within 30 calendar days. The practical consequence runs backwards from that deadline: a manager approaching the limit either stops adding vehicles or starts preparing the authorisation file long before the breach, because substance, governance, capital and documentation cannot be built in a month.
The regime is also a deliberate on-ramp. A registered AIFM may opt in to full authorisation at any time, taking on the complete AIFMD framework in exchange for the marketing passport and access to product regimes such as the RAIF. For managers whose strategy grows from deal-by-deal vehicles towards blind-pool funds, that sequencing, registered first, authorised when scale and distribution demand it, is the standard Luxembourg growth path.
File the Article 3 registration with the CSSF, with the AML/CFT IFM Market Entry Form through eDesk: identification of the manager, the AIFs managed, their strategies and the data needed to monitor AUM. File without delay; the CSSF treats two months from starting to manage the first AIF as the outer limit, reviews the file and confirms the registration. Notify each further AIF within 10 working days and update the registration form at least annually.
Under Articles 2 and 10 of Regulation 231/2013: all assets of all AIFs aggregated, derivatives converted into underlying exposure, leverage included, with cross-holdings between AIFs of the same external AIFM excludable to avoid double counting. Monitoring is ongoing, with at least an annual recalculation.
There is no AIFMD own-funds requirement, no depositary obligation for its unregulated AIFs and no remuneration or delegation framework. The capital rules of the manager's legal form, and of any other licence it holds, still apply, as do AML/CFT obligations and annual regulatory reporting.
Not with the AIFMD passport. Distribution runs under national private placement rules, country by country. Qualifying venture managers can consider the EuVECA label, which carries its own passport below the AIFMD thresholds.
A RAIF, no: it requires an authorised AIFM. Beyond unregulated SCSp vehicles, a registered AIFM may however, subject to the thresholds and product-level requirements, also manage certain CSSF-authorised funds, including SIFs, SICARs and Part II UCIs.
Notify the CSSF; if the excess is more than temporary (likely to last over three months), apply for authorisation within 30 calendar days. Voluntary opt-in is available at any time and is the standard growth path to the passport and the RAIF.
Fundequate Platform implements six record-design rules for Luxembourg AIFs: one investor identifier, dated events, preserved calculations, notice-level reconciliation, four-eyes approval and LPA-controlled configuration.
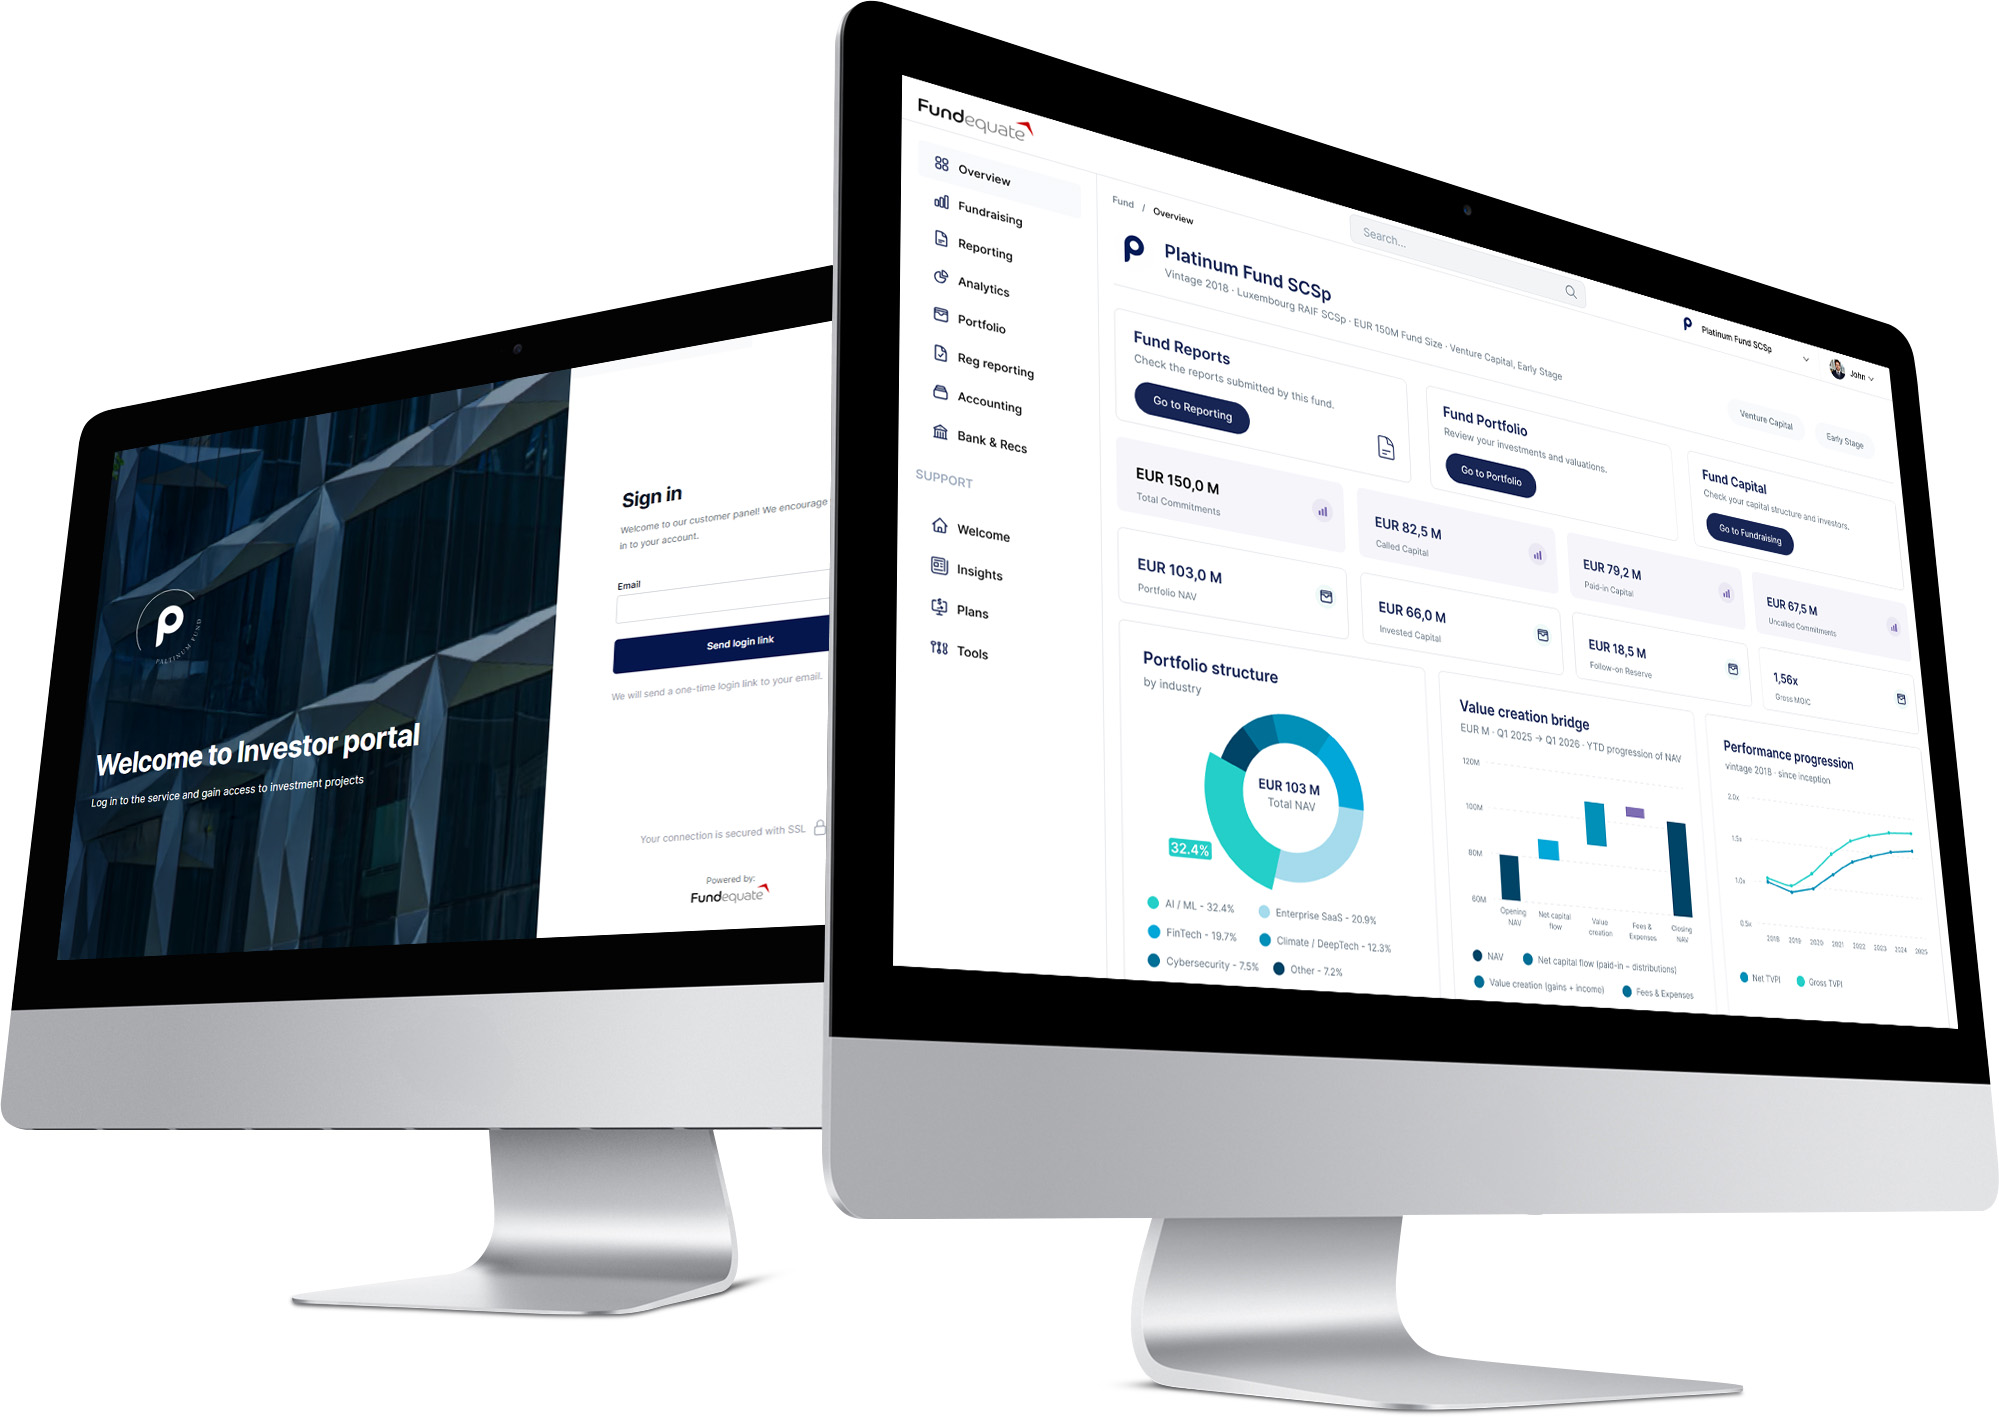
Investor onboarding, commitments and closings, capital calls, distributions, capital accounts and waterfall — with an LP portal, full audit trail and Invest Europe-aligned reporting.
Incorporation, RCS and RBE registration, bookkeeping, statutory accounts, VAT and annual filings, registered office and Luxembourg-resident management — the full substance layer for your fund vehicle.
Fundequate Sàrl is a company registered and domiciled in Luxembourg. We provide innovative solutions to simplify fund structuring, administration, and investor onboarding, ensuring compliance, transparency, and efficiency for fund managers and investors.


Fundequate Sarl
2 Rue Siggy vu Letzebuerg
L-1933 Luxembourg
contact@fundequate.com
Tel. +352 661 324 404
