Article 1(9) of the Law of 12 July 2013 on alternative investment fund managers defines marketing as a direct or indirect offering or placement, at the initiative of the AIFM or on its behalf, of units or shares of an AIF it manages, to or with investors domiciled or with a registered office in the European Union. Three consequences follow for anyone raising money into an SPV.
Whether the SPV is an AIF in the first place is a prior question, covered in Is a Luxembourg SPV an AIF?. Everything below assumes it is, which is the usual position for a deal-by-deal vehicle with passive outside investors, as explained in the deal-by-deal SPV guide.
The CSSF FAQ on the Law of 12 July 2013 (version 24, 20 May 2025, section 21) gives the working test: marketing takes place when the AIF, the AIFM or an intermediary on their behalf seeks to raise capital by actively making units available for firm purchase. The form is irrelevant (advertising, documents, roadshows, distance marketing); the decisive element is whether the material can be used to formally subscribe or commit.
| Situation | Marketing? | CSSF FAQ |
|---|---|---|
| Subscription agreement, commitment form or a link to sign one | Yes | 21.A, 21.D |
| Draft documents that cannot be used to subscribe or commit | No, but presenting them at the AIFM's initiative ends any later reliance on reverse solicitation by those investors | 21.B, 21.C |
| Website, email or call reaching an investor domiciled in Luxembourg, with usable subscription material | Yes, as distance marketing in Luxembourg | 21.H |
| Investment by a discretionary portfolio manager on behalf of its client | No, where the investment is independently initiated by the portfolio manager, as described in the CSSF FAQ | 21.M |
| Recommendation by an investment adviser to its client | No, where the recommendation is independently initiated by the adviser, as described in the CSSF FAQ | 21.N |
| Investment by another fund or its manager | No, where the investment is independently initiated by that fund or its manager, as described in the CSSF FAQ | 21.O |
| Secondary transfer between investors | No, unless intermediaries act at the initiative or on behalf of the AIFM or the AIF | 21.P |
The CSSF itself notes that marketing has no single European definition and that other authorities may read it differently. A Luxembourg reading is a starting point, not a guarantee of the position in the investor's country.
Under the AIFM Law the categories are binary: professional investors and everyone else (retail investors). For marketing in Luxembourg, the CSSF FAQ (section 12, preliminary remark and item 12.D) states the rule for Luxembourg AIFs not authorised by the CSSF: marketing is limited to professional investors, with the RAIF as the only exception, which may be marketed to well-informed investors under the Law of 23 July 2016. A RAIF requires an authorised AIFM. For an unregulated SCSp under a registered AIFM, the invitable population in Luxembourg is therefore professional investors only.
The AIFM Law borrows the definition from Annex II to MiFID II (Directive 2014/65/EU). Section I lists clients treated as professional by default: credit institutions, investment firms, insurers, pension funds and their managers, other collective investment undertakings and their managers, other authorised or regulated financial institutions, large undertakings meeting two of three size tests (balance sheet EUR 20 million, net turnover EUR 40 million, own funds EUR 2 million), national and regional governments and public bodies, central banks and supranational institutions, and other institutional investors whose main activity is investing in financial instruments.
Section II allows other investors, including individuals and family holding companies, to be treated as professional. It is a procedure, not a box to tick:
Meeting two quantitative criteria does not automatically confer professional status. The relevant assessment and opt-up procedure must be completed before the investor is treated as professional for the intended transaction.
Practical rule: run the opt-up before the investor receives anything usable to subscribe. An opt-up completed after the subscription link was sent does not cure an invitation that was made to a retail investor.
Marketing AIFs to retail investors in Luxembourg is governed by Article 46 of the Law of 12 July 2013. It is open only to authorised AIFMs, and only for AIFs under permanent supervision in their home state; for Luxembourg funds that means Part II UCIs under the Law of 17 December 2010, with SIFs and SICARs restricted to well-informed investors by their own laws. An unregulated SPV under a registered AIFM has no route to retail marketing in Luxembourg.
A registered AIFM has no AIFMD passport, so every invitation to an investor outside Luxembourg is a national private placement. Private placement is not an exemption from marketing: it is marketing carried out under the investor's national regime. Each EU country decides whether, and on what conditions, a registered manager from another Member State may market there. Germany, for example, provides a national marketing route for qualifying registered EU AIFMs under Section 330a of the Investment Code (KAGB), to professional and semi-professional investors, subject to registration in the home Member State, a reciprocity requirement and a notification to BaFin. Reciprocity is the decisive condition for Luxembourg managers: the home state must allow German registered managers to market there on conditions no stricter than the KAGB, while the CSSF FAQ (section 12) requires managers from other Member States to be authorised to market EU AIFs in Luxembourg. A Luxembourg registered AIFM should therefore not plan German fundraising on Section 330a without confirming the position with BaFin first. Other countries impose their own notifications, investor tests or simply no route at all. National rules also change, so the position is confirmed per country before the first invitation, not after the first commitment.
For a manager running many SPVs, the work reduces to five gates applied to every invitation:
The record gate matters more than it seems. Supervisors and auditors ask for evidence after the closing, and an SPV structure with dozens of vehicles produces hundreds of separate invitation decisions.
The definition covers placement "on behalf of the AIFM". A syndicate lead may engage in marketing or regulated placement activity where they actively offer AIF interests, particularly when acting on behalf of the AIFM. Merely introducing potential investors or sharing preliminary information does not automatically amount to placing units, but the actual activity, mandate and remuneration arrangements must be assessed. A lead who sends subscription documents or collects commitments is on the placement side of that line, and where the lead acts for the manager, the same gates apply to the lead's list as to the manager's own.
The cleanest structures make the lead a contractual part of the manager's process: the lead proposes names, the manager applies the gates and sends the subscription material. The lead's role in the vehicle itself, as adviser or co-investor, is described in the SCSp guide.
The CSSF FAQ (items 21.I to 21.L) describes reverse solicitation as providing information about an AIF and making its units available following an initiative of the investor or the investor's agent, without any solicitation by the AIF, the AIFM or an intermediary on their behalf in relation to that AIF. It is not marketing only where both cumulative components are met:
The AIFM carries the burden of proof, and the CSSF states plainly that reverse solicitation may never be invoked to circumvent the Directive. Reverse solicitation is also not an investor category: it removes the marketing qualification of the contact, but it does not lift other restrictions arising from the law, the fund documents or the product regime. What usually destroys it in an SPV context:
Evidence pack per reverse-solicitation investor: the first inbound message with its date and channel; a written confirmation by the investor, drafted in their own terms, that the approach was theirs and concerned the specific AIF; and a check of the manager's and the lead's outbound records showing no earlier contact about that AIF.
Since 2 August 2021, Article 30a AIFMD, transposed in Article 28-1 of the Law of 12 July 2013, gives authorised AIFMs a harmonised way to test investor interest in an AIF that is not yet established or not yet notified for marketing. The conditions:
The price of that regime is the 18-month rule in Article 28-1(2): any subscription by professional investors, within 18 months of the start of pre-marketing, into an AIF referred to in the pre-marketing or established as a result of it, is deemed to result from marketing and requires the marketing notification. Reverse solicitation is closed for that period.
The harmonised regime is written for authorised AIFMs. ESMA has expressly confirmed in Q&A 1070 (13 June 2023) that the Article 30a pre-marketing notification requirements do not apply to registered AIFMs, other than EuVECA or EuSEF managers, unless national law provides otherwise. A registered manager tests interest under the general Luxembourg test and the investor's national rules: drafts that cannot be used to subscribe are not marketing under item 21.B, but they still count as solicitation for reverse-solicitation purposes.
An unregulated SPV, such as an SCSp under a registered AIFM, may only be marketed to professional investors in Luxembourg. Retail marketing runs through Article 46 of the Law of 12 July 2013, reserved to authorised AIFMs and supervised AIFs such as Part II UCIs. A retail investor arriving by genuine reverse solicitation is not marketed to, but admitting one still brings PRIIPs KID obligations and should be a deliberate, documented decision.
Private placement is not an exemption from marketing; it is marketing under a national regime instead of the AIFMD passport. An invitation to subscribe sent to selected investors in one country is still marketing under Article 1(9) of the Law of 12 July 2013 and needs a legal basis in the investor's country.
Under the CSSF test, marketing requires material usable to subscribe or commit, so a general post with no subscription route is usually not marketing in itself. A public post containing a subscription link may constitute marketing in jurisdictions where the offering is directed at investors; mere technical accessibility does not necessarily establish marketing in every jurisdiction. A prior communication promoting a specific AIF may also prevent reliance on reverse solicitation by investors reached through that communication.
Keep the investor's first message with date and channel, a written confirmation from the investor that the approach was theirs and concerned the specific AIF, and a record showing nothing about that AIF was sent to them before. The AIFM carries the burden of proof (CSSF FAQ, item 21.L).
Only on the same terms as anyone else. AIFMD has no private-circle or small-number exemption; a personal invitation to subscribe is marketing, and in Luxembourg an unregulated AIF may be marketed to professional investors only. Friends who pass the MiFID II assessment and opt-up procedure can be treated as professional on request; others cannot be invited to subscribe.
An investor treated as a professional client under Section II of Annex II to MiFID II after a qualitative assessment and at least two of three tests: ten significant transactions per quarter over four quarters, a portfolio above EUR 500,000, or one year in the financial sector in a relevant position. The investor requests it in writing, receives a written warning and confirms awareness in a separate document. Meeting the tests does not by itself confer the status.
The harmonised regime of Article 30a AIFMD and Article 28-1 of the Law of 12 July 2013 is written for authorised AIFMs; ESMA Q&A 1070 confirms the notification does not apply to registered AIFMs unless national law provides otherwise. A registered AIFM tests interest under national rules and the general marketing test: drafts that cannot be used to subscribe are not marketing under the CSSF FAQ, item 21.B.
AIF units are packaged investment products under Regulation (EU) No 1286/2014. A KID is required before the product is made available to a retail investor; an SPV admitting professional investors only does not need one.
Fundequate Platform implements six record-design rules for Luxembourg AIFs: one investor identifier, dated events, preserved calculations, notice-level reconciliation, four-eyes approval and LPA-controlled configuration.
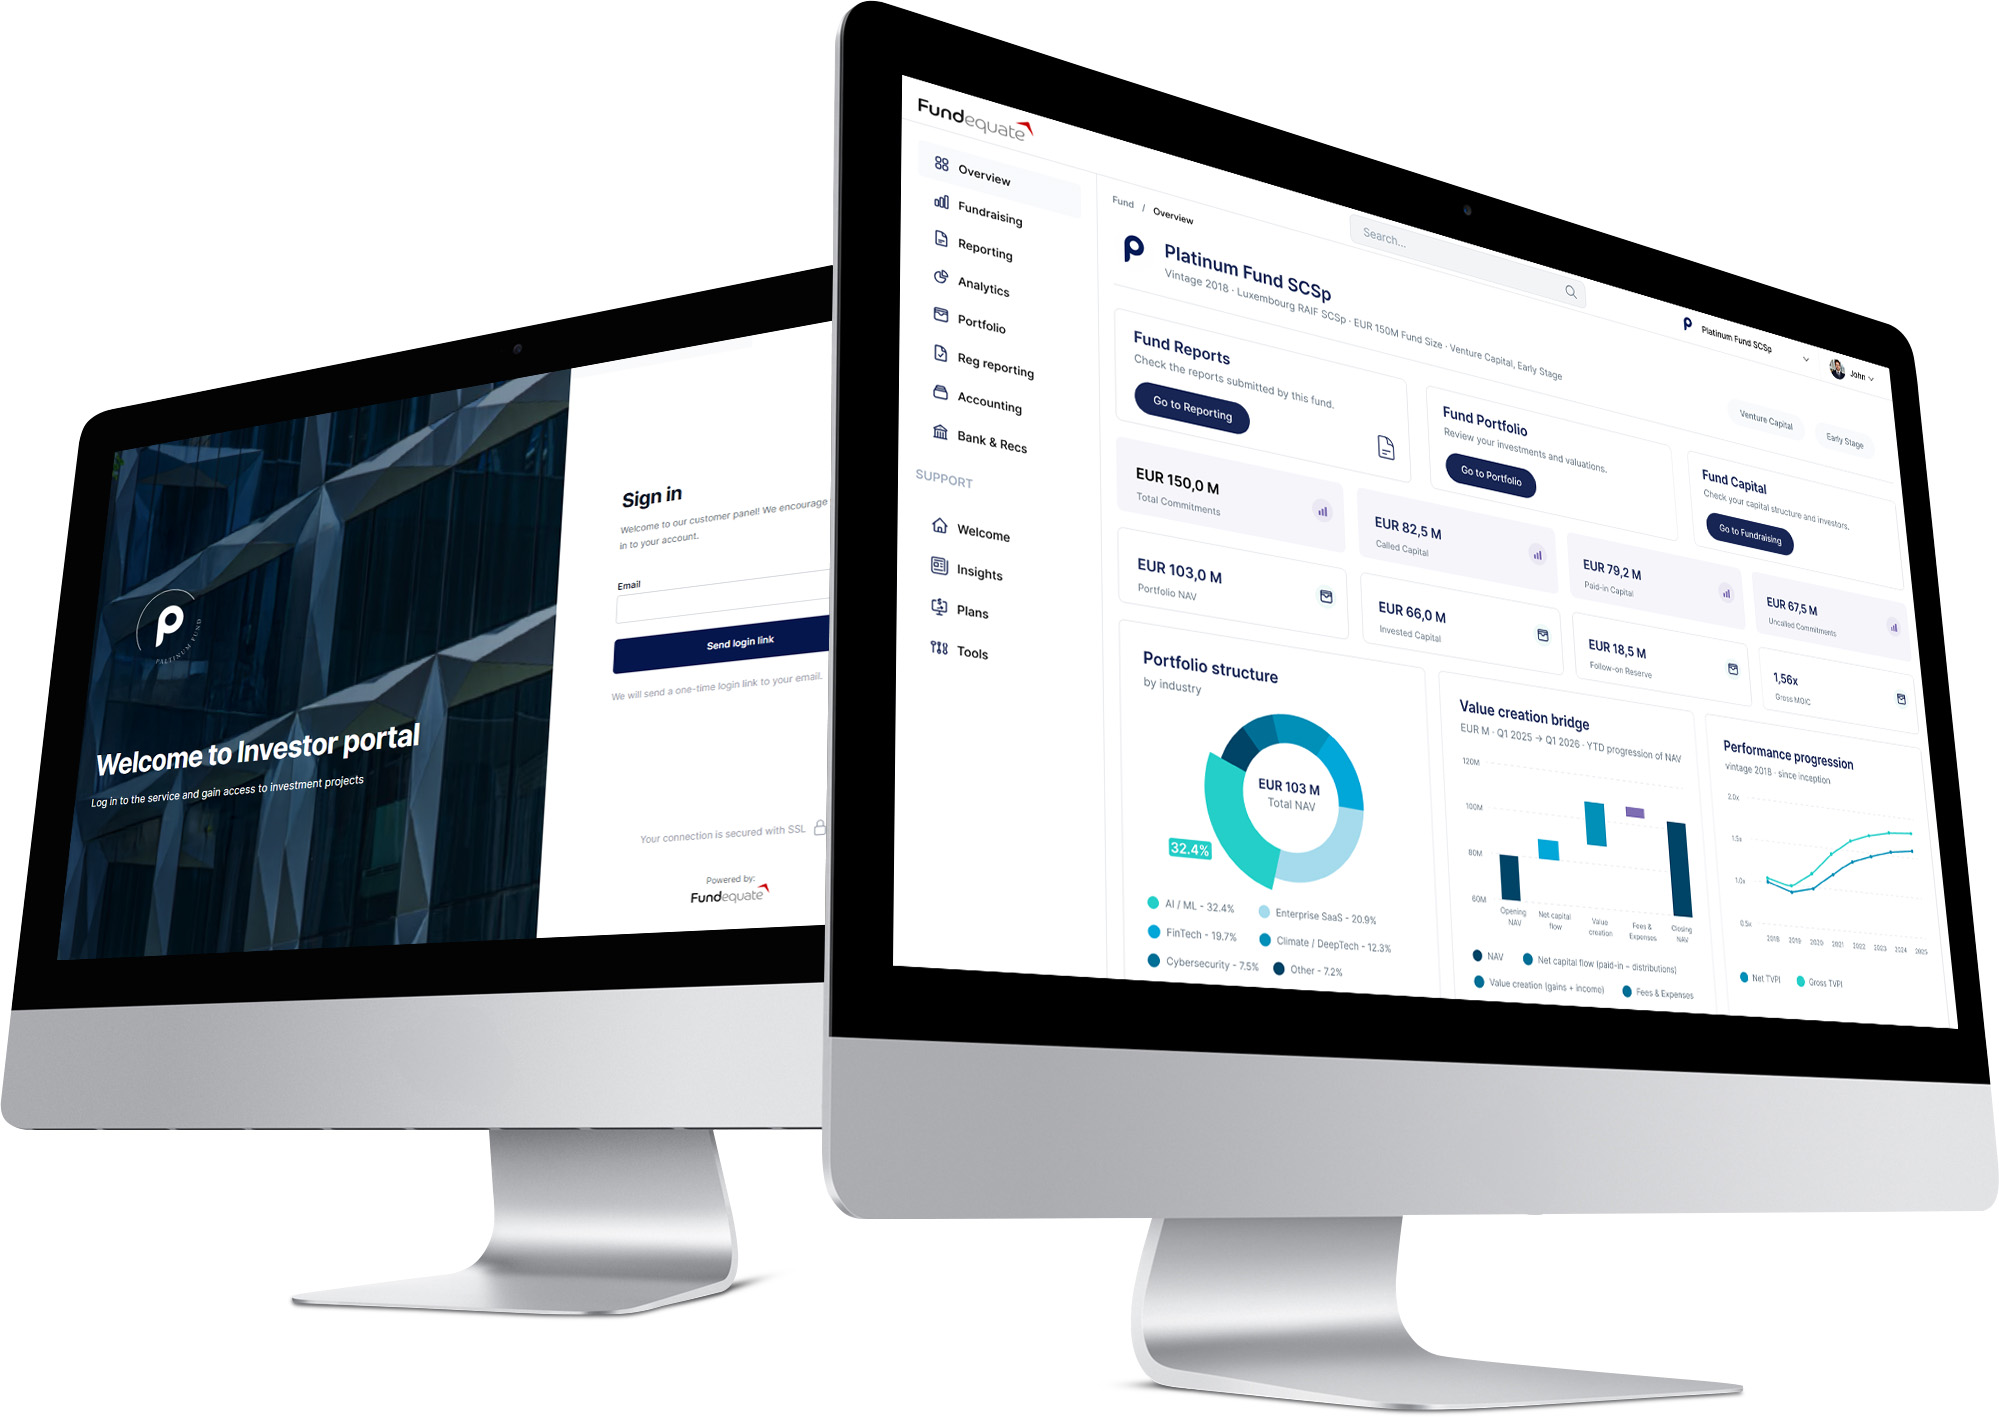
Investor onboarding, commitments and closings, capital calls, distributions, capital accounts and waterfall — with an LP portal, full audit trail and Invest Europe-aligned reporting.
Incorporation, RCS and RBE registration, bookkeeping, statutory accounts, VAT and annual filings, registered office and Luxembourg-resident management — the full substance layer for your fund vehicle.
Fundequate Sàrl is a company registered and domiciled in Luxembourg. We provide innovative solutions to simplify fund structuring, administration, and investor onboarding, ensuring compliance, transparency, and efficiency for fund managers and investors.


Fundequate Sarl
2 Rue Siggy vu Letzebuerg
L-1933 Luxembourg
contact@fundequate.com
Tel. +352 661 324 404
